Types of property investment strategies for clients
TL;DR:
- Property investment strategies are broadly categorized into active ownership and passive managed investments.
- The 2026 tax changes make selecting the right strategy more important for investor outcomes.
Property investment strategies fall into two broad categories: active direct ownership and passive managed investments. MoneySmart identifies three core vehicles clients use: direct property, managed investments, and self-managed super funds (SMSFs). Each vehicle carries different implications for control, tax treatment, and compliance. The 2026 Federal Budget introduced changes to negative gearing and capital gains tax that make choosing the right strategy more consequential than ever. Whether you are building a portfolio from scratch or diversifying an existing one, understanding the full range of real estate investment types is the starting point for every sound decision.
1. What are the main types of property investment strategies clients use?
Navy Federal classifies six core real estate investment strategies: residential rentals, commercial rentals, flipping, house hacking, REITs, and mutual funds or ETFs. This framework is the clearest map available for clients comparing active versus passive property investment options. Active strategies require hands-on management and direct ownership. Passive strategies trade control for lower effort and broader diversification.
The choice between active and passive is not purely about preference. It reflects your available time, capital, risk tolerance, and tax position. MoneySmart stresses that the initial choice of investment vehicle is as critical as the strategy itself, because control and tax outcomes differ significantly across vehicles.
2. Buy and hold residential rentals
Buy and hold is the most widely used active property investment method in Australia. You purchase a residential property, rent it out, and hold it for long-term capital growth while collecting rental income. The strategy suits investors who want steady cash flow and are comfortable managing a tenancy or paying a property manager.
Key features of buy and hold:
- Generates ongoing rental income to offset mortgage costs
- Benefits from long-term capital growth in rising markets
- Qualifies for negative gearing deductions where expenses exceed income
- Requires active oversight of maintenance, tenants, and compliance
- Exposes investors to vacancy risk and interest rate movements
The 2026 changes to negative gearing rules affect how this strategy performs on paper. Investors should model their after-tax returns carefully before committing.
Pro Tip: Research suburb-level vacancy rates and rental yield data before selecting a buy and hold property. A low vacancy rate signals consistent tenant demand, which directly protects your income stream.
3. Fix and flip properties
Fix and flip involves purchasing a property below market value, renovating it, and selling it for a profit within a short timeframe. This is a high-effort, high-reward strategy that suits investors with renovation experience and access to reliable trades. The margin between purchase price, renovation cost, and sale price determines your return.
The risks are real. Cost blowouts, longer-than-expected sale timelines, and capital gains tax on the profit can erode returns quickly. The 2026 capital gains tax changes make it worth modelling your net profit after tax before committing to a flip project.
4. House hacking: live in and earn
House hacking is a live-in investment strategy where you purchase a property, occupy part of it, and rent out the remaining rooms or a self-contained dwelling on the same title. It is one of the most accessible entry points for first-time investors because rental income offsets your mortgage repayments directly.
A common example is purchasing a duplex, living in one side, and renting the other. Another is buying a home with a granny flat and renting that separately. The strategy reduces your personal living costs while building equity and generating income simultaneously.
5. Remote ownership with a property manager
Remote ownership means purchasing an investment property in a location you do not live in, then appointing a local property manager to handle day-to-day operations. This approach opens access to markets with stronger rental yield or capital growth than your home city may offer.
Property management fees typically run between 7% and 12% of weekly rent, depending on the state and service level. That cost is tax-deductible but reduces net yield. The strategy suits investors who prioritise market selection over convenience.
6. Real estate investment trusts (REITs)
REITs are publicly listed or unlisted funds that own income-producing properties. You buy units in the trust rather than a physical property. NerdWallet notes that REITs act like stocks but package property selection and management decisions at the portfolio level, meaning investors assume manager risk rather than individual property risk. That is a nuanced but important distinction.
Listed REITs trade on the Australian Securities Exchange (ASX), giving you liquidity that direct property cannot match. Unlisted REITs are less liquid but may offer higher yields. Both types distribute income regularly, making them attractive for clients who want property exposure without the management burden.
7. Crowdfunding and co-investment platforms
Property crowdfunding platforms pool capital from multiple investors to fund development projects or acquire income-producing assets. Rocket Mortgage describes this as a passive investing option that trades control for diversification and lower effort, while still carrying risk and shared profit structures. Minimum investment amounts vary by platform and project type.
The key advantage is access. Crowdfunding lets you participate in commercial or development projects that would otherwise require far more capital. The key risk is illiquidity. Your capital is typically locked in for the duration of the project, which can span several years.
8. Real estate mutual funds and ETFs
Property ETFs and mutual funds invest across a portfolio of listed property securities, including REITs and property companies. They offer broad diversification across sectors such as retail, industrial, and residential within a single investment. Management fees are generally lower than unlisted funds, and you can buy and sell units on the ASX like any share.
NerdWallet distinguishes these from physical ownership by noting that indirect exposure reduces management time and risk concentration. The trade-off is that returns are tied to market sentiment as well as underlying property performance.
9. Passive investment strategies compared
| Strategy | Minimum investment | Effort level | Liquidity | Control |
|---|---|---|---|---|
| Listed REITs | Low (ASX units) | Very low | High | None |
| Unlisted REITs | Medium | Very low | Low | None |
| Property ETFs | Low (ASX units) | Very low | High | None |
| Crowdfunding | Medium | Low | Very low | Minimal |
| Property mutual funds | Medium | Very low | Medium | None |
Passive strategies suit clients who want property exposure without the time commitment of direct ownership. The trade-off, as Rocket Mortgage warns, is that passive investing still involves risk and reliance on managers, even when your personal effort is minimal.
10. SMSF property investing
An SMSF (self-managed super fund) allows trustees to purchase property directly using superannuation savings. Smart Property Investment explains that SMSF property investing offers control but requires strict compliance with sole-purpose rules and operational responsibilities that make it unlike a standard buy-to-let investment.
Key rules and steps for SMSF property investing:
- Establish a compliant SMSF with a corporate trustee structure
- Develop and document an investment strategy that includes property
- Purchase property at arm’s length, with no related-party transactions for residential assets
- Use a Limited Recourse Borrowing Arrangement (LRBA) if borrowing is required
- Ensure the property is used solely for retirement purposes
- Maintain separate accounts and annual audits as required by the ATO
RSM Australia clarifies that SMSF property is more complex than schemes like the First Home Super Saver and that strict arm’s-length rules apply throughout the ownership period. Commercial property held in an SMSF can be leased to a related business, which is a significant advantage not available with residential property.
Pro Tip: Consult a licensed SMSF specialist and a property adviser before proceeding. The compliance obligations are ongoing, not just at purchase, and the penalties for breaches are severe.
11. How to choose the right strategy for your goals
Choosing among the best property investment methods comes down to four factors: your available capital, the time you can commit, your risk tolerance, and your tax position. SmartAsset recommends separating asset class from strategy when building a portfolio. Diversifying across residential, commercial, and industrial assets reduces risk beyond simply owning multiple properties of the same type.
Key decision factors to weigh:
- Capital available: Direct ownership requires a deposit and borrowing capacity. REITs and ETFs require far less.
- Time commitment: Active strategies like buy and hold or flipping demand ongoing attention. Passive options like REITs require almost none.
- Risk tolerance: Direct ownership concentrates risk in one asset. Funds spread it across many.
- Tax position: Negative gearing suits high-income earners. The 2026 changes to capital gains tax affect both active and passive returns differently.
- Control preference: Direct ownership gives full control. Managed funds give none.
A well-structured investment plan aligns your strategy with your financial goals before you commit capital. Mixing active and passive approaches across different asset classes is the most resilient model for long-term portfolio diversification.
Key takeaways
The most effective property investment strategy combines direct ownership for control and growth with passive vehicles for diversification and lower effort, adjusted for your tax position and the 2026 regulatory environment.
| Point | Details |
|---|---|
| Active vs passive divide | Active strategies like buy and hold require management; passive options like REITs require almost none. |
| SMSF complexity | SMSF property investing demands strict compliance and is distinct from standard investment approaches. |
| Tax changes matter | The 2026 negative gearing and capital gains tax changes affect which strategies deliver the best after-tax returns. |
| Diversify across asset classes | Spreading investment across residential, commercial, and industrial assets reduces concentration risk. |
| Vehicle choice is critical | The investment vehicle you choose determines your control, tax treatment, and compliance obligations. |
Wealthstacker helps you compare and track your property strategy
Choosing among the types of property investment strategies available to clients is easier when you can model the numbers in real time. Wealthstacker is a property investment toolkit that provides automated quarterly valuations at no cost, so your portfolio data stays current without manual effort.
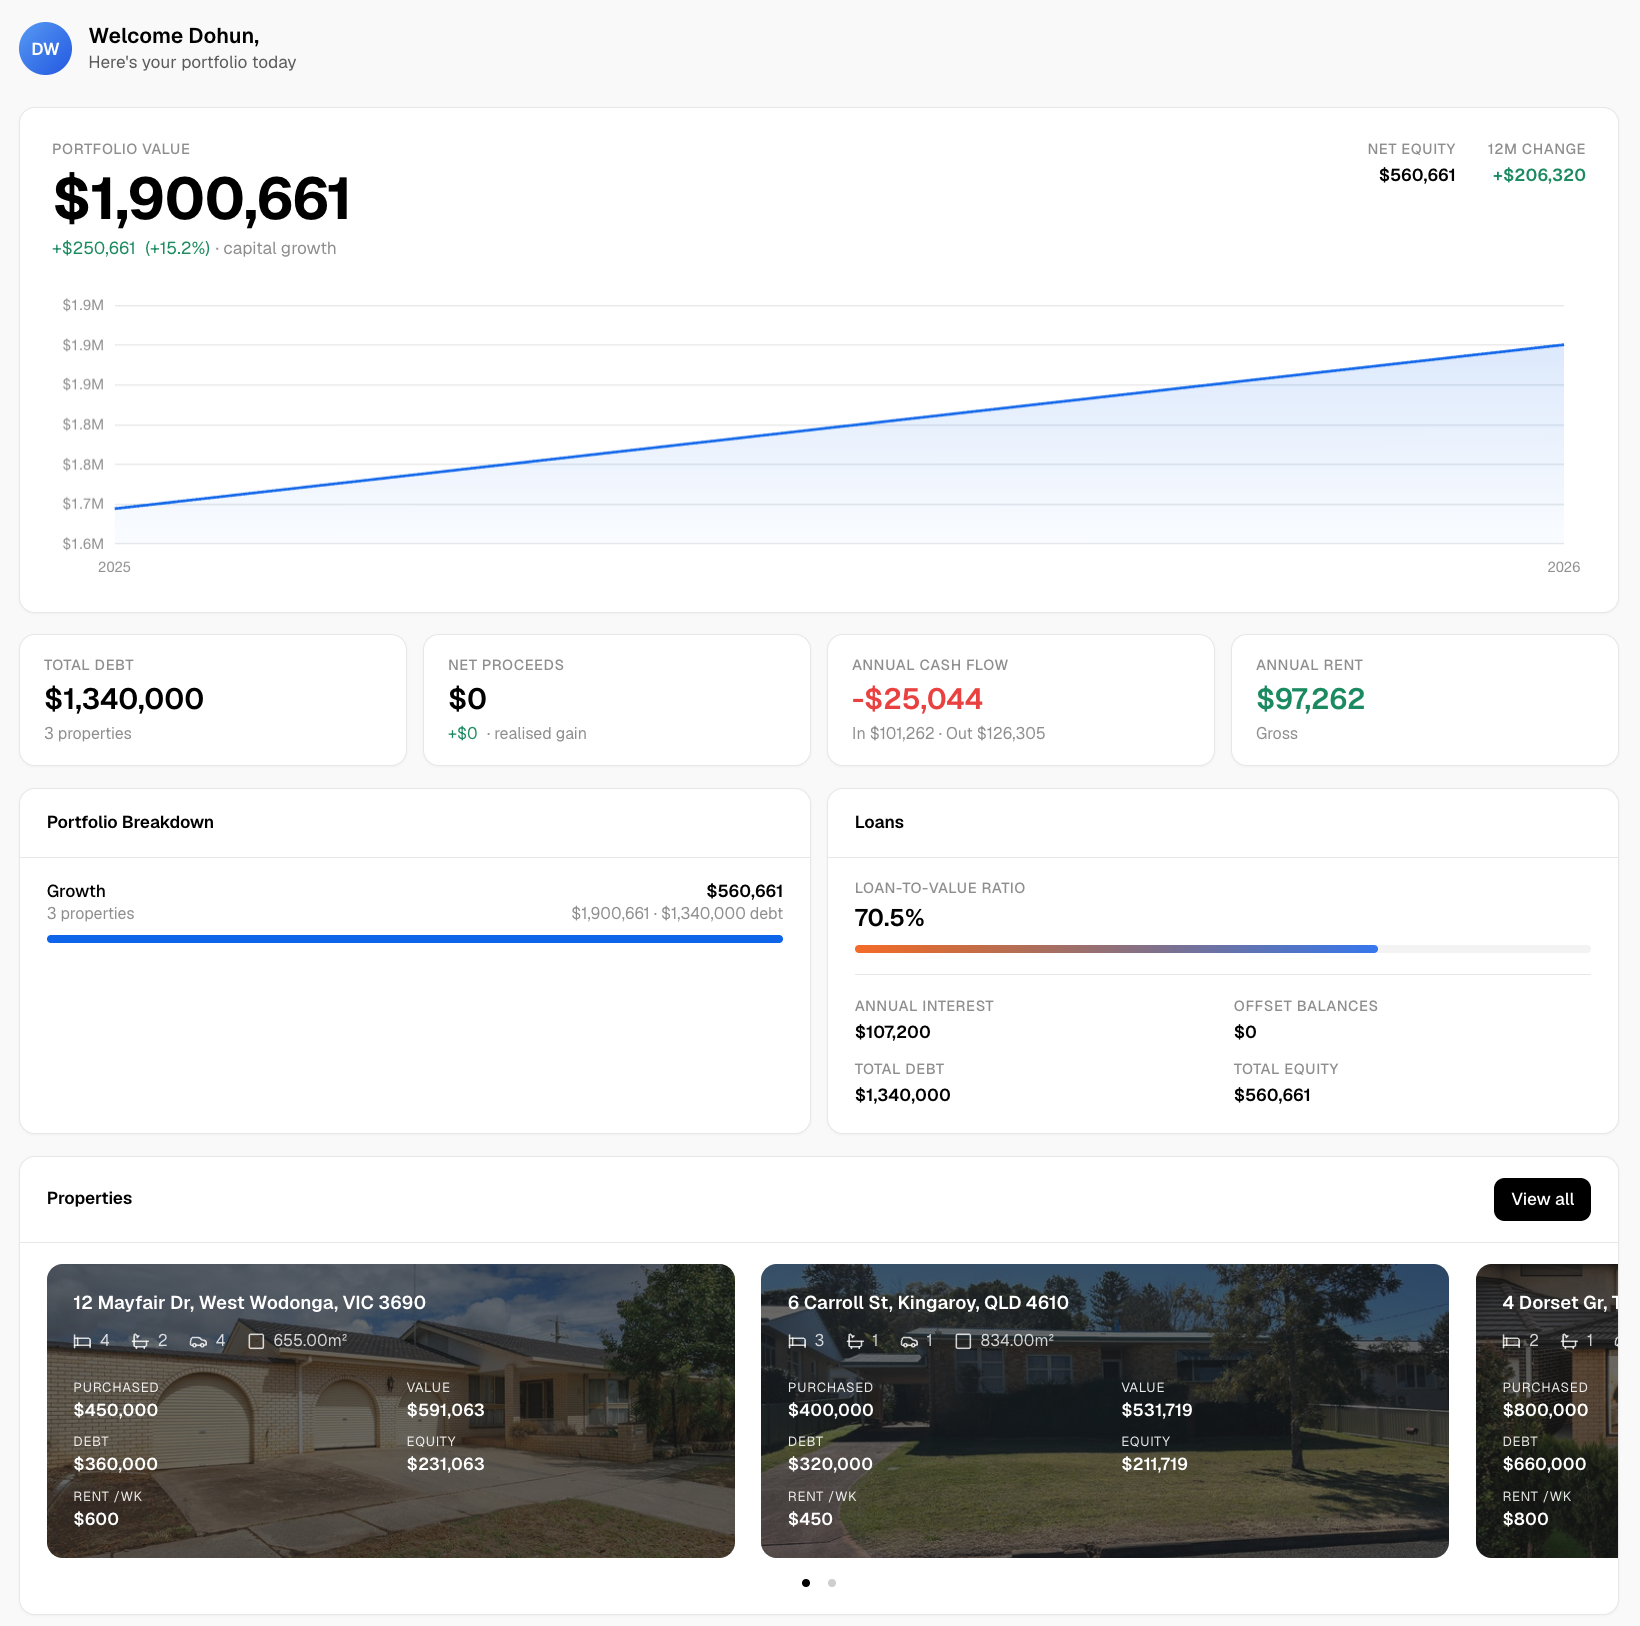
Wealthstacker’s AI tools let you model both rentvesting and direct ownership scenarios side by side, showing projected net worth over time based on your borrowing power and chosen strategy. Whether you are evaluating your first buy and hold property or comparing REITs against direct ownership, the Wealthstacker portfolio tracker gives you the forecasts and path planning to make a confident, informed decision.
FAQ
What are the main types of property investment strategies?
The main types are direct ownership (buy and hold, flipping, house hacking), passive managed investments (REITs, ETFs, crowdfunding), and SMSF-based property investing. Each differs in effort, control, and tax treatment.
Is passive property investing risk-free?
Passive property investing is not risk-free. Rocket Mortgage notes that passive options like REITs and crowdfunding still carry risk and rely on manager performance, even though your personal effort is minimal.
Can I use my superannuation to buy an investment property?
Yes, through an SMSF. RSM Australia confirms that SMSF property investing involves strict arm’s-length rules, borrowing frameworks like LRBAs, and ongoing compliance obligations that differ significantly from standard property purchases.
How do the 2026 tax changes affect property investment strategies?
The 2026 Federal Budget introduced changes to negative gearing and capital gains tax that alter after-tax returns for both active and passive strategies. MoneySmart recommends consulting the ATO for current details before committing to a strategy.
What is the best property investment strategy for beginners?
Buy and hold residential rentals or listed REITs are the most accessible starting points. Buy and hold builds equity and income over time, while REITs offer property exposure with low minimum investment and no management responsibility.