Market cycles decide when to lean in, not when to jump
Use market cycles as context for your allocation and rebalancing decisions, never as a calendar for calling tops and bottoms. Set your strategic asset allocation first. Rebalance on a fixed rule, such as annually or whenever an asset class drifts 5% from its target. Only then consider small, documented tactical tilts, and only when you understand the costs and have a clear exit rule.
Funds SA makes exactly this case: cycles are real, but the sensible response is structural patience and rebalancing, not forecasting. Fidelity’s business-cycle research backs this with historical data on how asset classes rotate through expansion and contraction. The catch is timing: official recession and recovery dates get announced months after the fact, a lag baked into how bodies like the NBER work. By the time a phase is confirmed, it is usually half over.
Here is the practical shortlist:
- Build your strategic allocation around your goals and risk tolerance, not your cycle guess.
- Rebalance on a rule (calendar or threshold), not on a hunch.
- Cap any tactical tilt at a small percentage of the portfolio, with a written hypothesis and exit point.
- Keep a liquidity buffer so you are never forced to sell during a downturn.
Missing the market’s best days is expensive. Multiple long-run studies of major equity indices show that a large share of total returns arrives in a small number of trading sessions, often clustered around volatile turning points, exactly when nervous investors are most likely to be sitting in cash.
Key Takeaways
Portfolio timing succeeds when investors treat market cycles as context for allocation and rebalancing decisions, not as a signal to predict exact turning points.
| Point | Details |
|---|---|
| Set strategy before tactics | Lock in your strategic allocation first; treat any cycle-based tilt as a small, capped adjustment on top. |
| Rebalance on a rule | Use a calendar or threshold rule (such as a 5% drift trigger) rather than reacting to headlines. |
| Respect the dating lag | Official cycle turning points are confirmed retrospectively, often months late, so treat stage labels as history, not signals. |
| Diversify cycle exposure in property | Sequence purchases across different growth rate cycle positions rather than buying multiple markets at the same phase. |
| Keep a liquidity buffer | Hold enough cash and structure debt so a rate spike or drawdown never forces a sale at the worst possible time. |
Table of Contents
- The role of market cycles in portfolio timing decisions
- How stocks, bonds, cash and property behave across the cycle
- Why trying to time cycle turns rarely pays off
- How to build portfolio rules around cycles instead of predictions
- Which indicators actually help you read where you are in the cycle
- Applying cycle rules to a property portfolio with WealthStacker
- Frequently asked questions
- Sources
The role of market cycles in portfolio timing decisions
Every market moves through recurring phases of expansion and contraction, and understanding those phases is the entire point of thinking about the role of market cycles in portfolio timing. A market cycle isn’t the same thing as a business cycle, though the two are tangled together. The business cycle tracks the real economy: GDP, employment, industrial output. The market cycle tracks asset prices, which usually move ahead of the economy because investors price in expectations, not history.
There are four phases worth knowing, and each has a rough diagnostic signature:
- Early cycle (recovery): growth turns positive after a trough, credit starts flowing again, and cyclical stocks tend to lead the rebound.
- Mid cycle (expansion): growth is steady and broad, earnings improve across most sectors, and this phase is often the longest of the four.
- Late cycle (mature expansion): growth slows from its peak rate, inflation and wage pressures build, and central banks typically start tightening.
- Recession (contraction): output shrinks, unemployment rises, and risk assets usually reprice sharply before the trough is confirmed.
What actually drives the rotation between these phases? Five forces do most of the work. GDP growth and corporate earnings set the fundamental backdrop. Monetary policy, meaning interest rate settings and central bank liquidity operations, either accelerates or chokes off credit growth. Investor sentiment amplifies both directions, turning ordinary slowdowns into panics and ordinary recoveries into euphoria. Seasonality plays a smaller but persistent role, particularly around fiscal year ends and index rebalancing dates.
One nuance trips up a lot of investors: markets tend to lead the economy, often by six to twelve months. Share prices usually start falling before a recession is officially confirmed, and they usually start recovering before unemployment peaks. This is why using economic data alone to time your portfolio moves is a losing game. By the time GDP figures confirm a recession, the market has often already priced in the recovery.
There’s a second layer worth understanding: the monetary cycle can lead the business cycle. Central bank policy shifts, rate cuts, rate hikes, changes in liquidity settings, often show up before the real economy responds. Research from Brocato and Steed explores this directly, finding that monetary-cycle indicators can shift the way asset classes move together (their correlation structure), which matters more for portfolio construction than most investors realise. If you are watching for signals, monetary policy tends to give you an earlier read than waiting for GDP or employment prints to confirm what has already happened.
None of this means you can reliably trade the transitions. It means you can understand why your portfolio behaves the way it does at different points, and adjust your expectations accordingly rather than panicking when a phase shift arrives.
How stocks, bonds, cash and property behave across the cycle
Different asset classes have historically preferred different phases, and knowing the general pattern helps you set realistic expectations rather than chase last quarter’s winner. None of this is a guarantee. It’s a tendency, observed across many cycles, that can and does break down in any single cycle.
Fidelity’s phase-by-phase research lays out the general pattern clearly:
- Early cycle: cyclical sectors (consumer discretionary, industrials, smaller companies) tend to lead because they benefit most from a credit and confidence rebound.
- Mid cycle: the rally usually broadens out, with technology and industrials often participating alongside the early leaders, and this is typically the longest phase.
- Late cycle: commodities and energy have historically held up better as inflation pressures build, while growth-sensitive cyclicals start losing steam.
- Recession: high-quality government and investment-grade bonds, along with defensive equity sectors like utilities and healthcare, tend to hold value better as growth contracts.
Cash sits slightly outside this framework. It rarely “outperforms” in any phase, but its value isn’t measured in returns. It’s measured in optionality: dry powder to rebalance into cheap assets during a downturn, or to cover expenses without selling into a falling market.
Property behaves differently again, moving on its own cycle that is partially tied to, but not perfectly synchronised with, equity market cycles. Property values respond more to interest rates and lending conditions than to corporate earnings, which is why residential and commercial property can lag or lead the broader market cycle depending on how sensitive local lending is to rate changes.
Three things change across cycles, and one thing usually doesn’t. Valuations shift, sometimes dramatically. A price to earnings ratio of 25 in a late cycle boom can compress to 14 within eighteen months without a single dollar of earnings changing, purely on sentiment and discount rate shifts. Correlations shift too. Assets that appeared uncorrelated during calm mid cycle conditions often move together during a liquidity crunch, which is exactly when diversification benefits investors need most tend to disappear. Liquidity conditions change, meaning how easily and cheaply you can buy or sell without moving the price, and this tightens noticeably in late cycle and recession phases.
What tends to stay more stable, over long periods, is the underlying return driver for each asset class. Equities are still ultimately driven by earnings growth and the price investors are willing to pay for that growth. Bonds are still driven by yield and credit risk. Property is still driven by rental yield and capital growth potential in the specific location. Cycles change the weather around these drivers. They don’t usually rewrite the drivers themselves.
The mistake many investors make is treating a valuation squeeze or a correlation breakdown as evidence the old rules no longer apply, and abandoning a sound long-term allocation in favour of chasing whatever asset class just had a strong run. Funds SA’s guidance on cycle investing makes the same point from a different angle: the sensible response to short-term dislocation is rebalancing back toward your target weights, not redesigning your strategy around the last six months of price action.
A practical takeaway: if you know cyclicals tend to lead early and defensives tend to hold up late, you can use that knowledge to set sensible tilt ranges around your core allocation, say, plus or minus five percentage points on a sector, rather than making binary all-in or all-out calls based on a guess about which phase you’re currently in.
Why trying to time cycle turns rarely pays off
The single biggest obstacle to market timing isn’t a lack of skill. It’s a lack of real-time information. Recession and recovery dates get confirmed retrospectively, often by committees like the NBER in the United States, sometimes six to twelve months after the turning point actually happened.
This retrospective dating problem is well documented in practitioner literature. As one detailed breakdown of market timing approaches notes, most timing signals that rely on confirmed cycle stages are structurally too slow to be useful for live decisions, because the confirmation itself lags the price move it’s meant to predict.
The problem with using officially dated business cycle turning points as a trading signal isn’t that the dates are wrong. It’s that they arrive too late to trade on, which means any strategy built around waiting for confirmation is really a strategy built around missing the move.
Academic work on this isn’t uniformly negative. Brocato and Steed’s research found that using an ex-ante monetary policy indicator, something observable in real time rather than confirmed after the fact, could improve portfolio efficiency in-sample. That’s a meaningful distinction: a signal you can observe as it happens (like a rate decision) behaves very differently to a signal that only exists once a committee has looked backward and agreed on a date. But even here, the caveats matter. In-sample results don’t always hold up out-of-sample, and the paper is explicit that practical implementation carries real friction.
More recent practitioner testing reinforces the caution. Analysis from TheFinsense found that sector rotation strategies tied to business-cycle stages often increased portfolio volatility without clearly improving risk-adjusted returns once transaction costs were factored in, even under generous assumptions about timing accuracy.
The common failure modes are consistent across studies and across decades:
| Failure mode | What happens | Why it hurts returns |
|---|---|---|
| Whipsaw | Indicator flips signal repeatedly in choppy markets | Forces frequent trades that lock in losses on both sides |
| Missed best days | Investor sits in cash waiting for confirmation | A small number of trading days often drive a large share of long-run returns |
| Cost drag | Frequent tactical shifts trigger fees, spreads, and tax events | Erodes gross returns before net performance is even calculated |
| Higher realised volatility | Concentrated sector bets replace diversified exposure | Larger drawdowns during transitions, even if average returns look similar |
None of this means signals are worthless. It means the signal needs to be observable in real time, cheap to act on, and tested with realistic costs, not just backtested on confirmed dates that weren’t available when you needed them.
How to build portfolio rules around cycles instead of predictions
Trying to predict the exact top or bottom of a cycle is a losing game for almost everyone, including full-time professionals with better data than you’ll ever have. What works instead is a small set of rules you set up in advance, when you’re calm, and then follow regardless of what the headlines say. Here’s how to structure that.
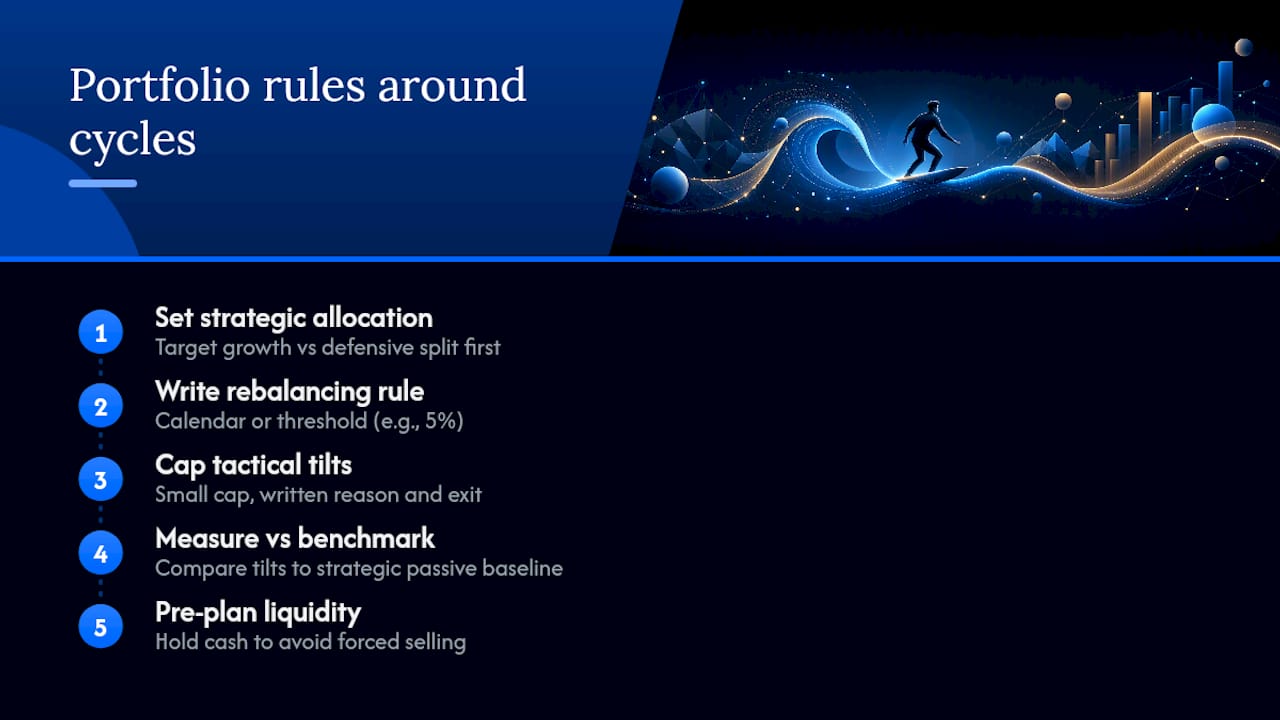
1. Lock in your strategic allocation before anything else. This is the split between growth assets (shares, property) and defensive assets (bonds, cash) that matches your goals, timeframe and genuine risk tolerance, not your risk tolerance on a good day. Research consistently points to strategic allocation as the dominant driver of long-run portfolio outcomes, well ahead of security selection or timing decisions. Get this right first, because everything else is a modification of it, not a replacement for it.
2. Choose a rebalancing rule and write it down. You have two broad options. Calendar rebalancing means you check and adjust your weights on a fixed schedule, annually or quarterly, regardless of what’s happened in between. Threshold rebalancing means you act whenever an asset class drifts a set amount from target, commonly 5%. A detailed look at rebalancing mechanics shows threshold rules tend to react faster to genuine cycle shifts, while calendar rules are simpler to run and cheaper on trading costs. Either works. What doesn’t work is having no rule and rebalancing whenever it “feels right”, because that’s when cycle anxiety makes the decision for you.
3. If you want tactical tilts, cap them hard. A tactical tilt is a deliberate, temporary deviation from your strategic weights based on a cycle view, say, overweighting defensives because you think the late cycle is ending badly. Fine, but cap it at a small percentage of the total portfolio, write down the specific reason you’re making the move, and set a date or condition for when you’ll unwind it if you’re wrong. Without a written exit rule, tilts have a habit of becoming permanent, half-forgotten bets that quietly wreck your diversification.
4. Measure the results honestly. Track whether your tilts actually added value against a simple benchmark of just holding the strategic allocation. Most investors who do this discover their tilts cost more than they earned once you account for the trades they made under stress. Benchmarking your portfolio performance against a passive baseline is the only honest way to know if your tilts are adding value or just adding noise.
5. Plan liquidity before you need it, not during a crisis. Late cycle and recession phases are exactly when credit tightens, asset prices fall, and forced selling does the most damage. Keep enough cash or liquid assets on hand that a rate spike or a market drawdown never forces you to sell growth assets at the worst possible moment. This matters as much for property investors managing loan serviceability as it does for share investors covering margin calls.
Pro Tip: Set your rebalancing threshold and your maximum tactical tilt size on the same day you write your investment plan, before you’ve experienced a single real drawdown. Decisions made in a calm moment are dramatically more disciplined than decisions made while your portfolio is down 15% and every headline is telling you to do something.
If you’re time-poor and worried about missing a rebalancing trigger altogether, a simple monitoring routine that checks your weights quarterly, even for five minutes, is usually enough to catch meaningful drift without turning portfolio management into a second job.
Which indicators actually help you read where you are in the cycle
You don’t need a bank of screens and a Bloomberg terminal to get a reasonable read on cycle conditions. A handful of widely available indicators, used together and with patience, do most of the useful work.
The yield curve, the spread between short-term and long-term government bond yields, is one of the more closely watched signals. An inverted curve, where short rates sit above long rates, has historically preceded recessions in many economies, though the lead time varies from months to well over a year, and false signals happen. It’s a probability shift, not a certainty.
Central bank policy shifts matter directly, not just as a symptom of the cycle but as a driver of it. Watching Reserve Bank of Australia statements on monetary policy gives you an observable, real-time read on where policy is heading, which is exactly the kind of ex-ante signal that Brocato and Steed’s research found more useful than waiting for retrospective cycle confirmation.
Valuation metrics, particularly price to earnings ratios measured against their own long-run average, tell you whether a market phase has run further than fundamentals justify. A market trading well above its historical valuation band in a late cycle environment is carrying more downside risk than the same market trading near its average.
Simple trend rules, such as watching whether a broad index sits above or below its 200-day moving average, give you a mechanical, low-emotion way to gauge momentum without needing to interpret ambiguous economic data.
Here’s how to combine them sensibly, because no single indicator should trigger a portfolio change on its own:
- Yield curve inversion plus stretched valuations: treat this combination as a signal to review your defensive allocation and liquidity buffer, not to sell everything.
- Trend break plus a genuine liquidity tightening (rising credit spreads, slowing loan growth): this combination is a stronger case for trimming a tactical overweight than either signal alone.
Wait for confirmation across at least two independent indicators before acting, and always weigh the signal against the cost of being wrong. A false signal that has you liquidating half your growth assets is a portfolio-altering mistake you might not recover from before the next cycle turns.
Applying cycle rules to a property portfolio with WealthStacker
Property investors face a distinct version of the timing trap: rather than buying and selling too often, the risk is buying too much, too fast, in markets that are all sitting at the same point in their growth rate cycle. If every property you own is exposed to the same local cycle phase, a single downturn hits your entire portfolio at once, which defeats the purpose of holding multiple properties in the first place.
The fix is sequencing, not timing. Rather than trying to predict when a specific suburb will boom, spread acquisitions across locations sitting at different points in their own cycle. Property portfolio diversification frameworks recommend exactly this: avoid concentrating purchases in markets that are all in the same growth phase, because that concentration is a hidden form of market timing risk, even if you never intended to time anything.
Rate cycles create a second, less obvious risk: borrowing capacity itself moves with the cycle. Lenders tighten serviceability tests as rates rise, which can strip borrowing power from investors exactly when property prices in some markets are becoming more attractive relative to income. Protecting against this means keeping a liquidity buffer, structuring debt so you’re not overly exposed to variable rate shocks, and staging acquisitions rather than deploying all your capital and borrowing power in one purchase during a single phase.
One data point worth sitting with: a large share of a property portfolio’s long-run resilience comes down to how spread out its cycle exposure is, not how well any single purchase was timed. Investors who buy across staggered cycle positions tend to smooth their overall equity growth compared with those who buy multiple properties in the same market during the same boom phase.
This is where a tool genuinely earns its place rather than just adding convenience. WealthStacker’s automated quarterly valuations let you track how each property in your portfolio is tracking against its local cycle without manually chasing valuation data every few months. Its 15 year scenario modelling helps you stress test a staged acquisition plan against different rate environments before you commit, and its borrowing power estimations flag how a rate cycle shift might affect your serviceability well before a lender’s tightening catches you off guard. Used this way, the platform doesn’t try to predict the next cycle turn. It helps you apply the same rule-based discipline to property that this article recommends for shares and bonds: know where each asset sits, rebalance your exposure deliberately, and keep enough buffer that a cycle shift is a manageable event rather than a crisis.
If you’re building out a broader property portfolio strategy, the sequencing principle above is worth applying from your very first purchase, not retrofitted after you’ve already concentrated risk in one market phase. For a look at the WealthStacker platform itself, the free tier covers automated valuations and portfolio tracking, which is enough to start applying cycle-aware sequencing without any upfront cost.
Frequently asked questions
Does timing the market ever work better than staying invested? Occasionally, by luck, but not reliably enough to build a strategy around. Studies of missed best trading days consistently show that investors who move to cash and wait for confirmation of a recovery tend to miss a disproportionate share of the market’s total long-run gains, since those gains often cluster in short, unpredictable bursts.
How often should I rebalance my portfolio around cycle shifts? Both approaches beat rebalancing on gut feeling, which tends to happen either too late or in a panic.
What’s the difference between the business cycle and the market cycle? The business cycle tracks real economic activity, GDP, employment, industrial production. The market cycle tracks asset prices, which typically move six to twelve months ahead of the economy because prices reflect expectations rather than confirmed data.
Can property investors avoid cycle risk entirely? Not entirely, but they can reduce concentration risk by sequencing purchases across different local markets sitting at different cycle positions, rather than buying several properties in the same boom phase in the same area.
Is it worth using tactical tilts at all, or should I just stick to a fixed allocation? A fixed strategic allocation with disciplined rebalancing is the stronger baseline for most investors. Small, capped tactical tilts can add value if you write down the reasoning and an exit rule in advance, but evidence on unconstrained sector rotation suggests the added volatility often outweighs any return benefit once costs are included.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- Investing through market cycles
- The business cycle: Equity sector investing | Fidelity
- Brocato & Steed — monetary cycle and portfolio efficiency (DOI:10.1111/1540-6288.00054)
- Market Timing Approaches
- Business cycle investing — practical critique and guidance | TheFinsense