Investment property forecasting methods: 2026 guide
TL;DR:
- Investment property forecasting methods use financial tools to project future returns and risk. Combining pro forma, discounted cash flow, DSCR, and Monte Carlo simulations offers a comprehensive risk and return analysis. Using multiple methods together enhances decision-making accuracy for real estate investments.
Investment property forecasting methods are analytical techniques that project future financial performance and investment returns for real estate assets. The most effective approach combines pro forma financial modelling, discounted cash flow (DCF) analysis, Debt Service Coverage Ratio (DSCR) assessment, and probabilistic techniques like Monte Carlo simulation. Each method serves a distinct purpose in real estate investment analysis, and using them together gives you a far more complete picture of risk and return than any single model can deliver.
1. What are investment property forecasting methods?
Investment property forecasting methods are structured financial tools used to project cash flow, returns, and risk over a defined investment horizon. They range from simple spreadsheet models to sophisticated probabilistic simulations. The goal is always the same: replace guesswork with evidence when deciding whether to buy, hold, or pass on a property.
The four methods covered here are pro forma modelling, DCF analysis, DSCR calculation, and Monte Carlo simulation. Each sits at a different level of complexity and serves a different decision. Pro forma is the foundation. DCF converts those projections into a present value. DSCR measures debt safety. Monte Carlo tests how outcomes shift when your assumptions are wrong.
Financial planners and property investors who use all four methods together make better decisions than those who rely on a single metric like gross yield or cap rate alone.
2. Pro forma financial modelling: the foundation of property forecasting
Pro forma modelling is the starting point for every serious property investment forecast. A standard pro forma starts with potential gross revenue and works down through vacancy, operating expenses, net operating income (NOI), debt service, and cash flow to equity. The result is a year-by-year income statement that shows exactly where money enters and exits the investment.
A well-built pro forma contains five core blocks:
- Assumptions tab: holds all key inputs including purchase price, rent growth rate, vacancy rate, and capital expenditure allowances
- Revenue schedule: projects gross rental income and deducts vacancy to arrive at effective gross income
- Expense schedule: itemises property management fees, insurance, rates, maintenance, and other outgoings
- Debt schedule: maps principal and interest payments across the loan term using the amortisation schedule
- Returns analysis: calculates Internal Rate of Return (IRR), Net Present Value (NPV), and cash-on-cash return
The pro forma is not a prediction. It is a structured set of assumptions that makes your thinking explicit and testable. When you change one input, such as vacancy rate or rent growth, you see the downstream effect on every return metric immediately.
Pro Tip: Build your pro forma with a dedicated assumptions tab that feeds all other calculations. This makes stress testing fast and reduces the risk of hardcoded errors buried in formulas.
Pro forma modelling also underpins more advanced methods by generating the cash flow estimates that DCF and Monte Carlo simulation then process. Skipping a rigorous pro forma means every downstream analysis inherits weak foundations.
3. How does discounted cash flow (DCF) analysis improve forecasting accuracy?
DCF analysis takes the cash flows produced by your pro forma and converts them into a single present value figure. DCF forecasting projects cash flows over a 5–10 year horizon and discounts them back using a required rate of return, producing NPV and IRR as the primary outputs. These two numbers tell you whether the investment creates or destroys value at your target return.
The key inputs in a DCF model are:
- Discount rate: your required rate of return, reflecting risk and opportunity cost
- Hold period: typically 5–10 years for residential and commercial investment property
- Terminal value: the estimated sale price at the end of the hold period, usually derived from an exit cap rate applied to the final year NOI
One common error is confusing the exit cap rate with the discount rate. These are related but not interchangeable. The discount rate equals the cap rate plus the long-run NOI growth rate, following the Gordon Growth model relationship. Mixing them up can materially misstate the property’s value.
A positive NPV means the investment exceeds your required return. A negative NPV means it does not. IRR tells you the annualised return the investment generates across the hold period. Together, these outputs turn a subjective “does this look good?” into a quantified buy or pass decision.
Pro Tip: Forecast operations unlevered first and apply debt as a separate scenario overlay. This separates asset-level returns from financing effects and makes your IRR results far easier to interpret.
4. What role does DSCR play in investment property forecasting?
Debt Service Coverage Ratio is the metric lenders and investors use to measure whether rental income covers debt obligations with enough margin to absorb a downturn. DSCR is calculated by dividing NOI by annual debt service. A result above 1.0 means the property generates more income than it costs to service the debt.
The standard benchmark is 1.25x. This means NOI is 25% higher than the annual mortgage payment, providing a buffer against vacancy spikes or unexpected expenses. A worked example illustrates the stakes: $99,600 NOI divided by $90,000 annual debt service produces a DSCR of 1.11. That result sits below the 1.25x threshold, signalling the investment carries meaningful debt risk even though it is technically cash flow positive.
Lenders use DSCR as a primary underwriting criterion for investment property loans. Investors should use it the same way, running the calculation before committing to a purchase price or loan structure. The inputs required are the lease agreements for income and the amortisation schedule for debt service.
DSCR works best alongside pro forma and DCF rather than in isolation. It answers a specific question: can this property service its debt safely? The other methods answer whether the investment creates wealth over time.
5. How do Monte Carlo simulations strengthen probabilistic forecasting?
Monte Carlo simulation is the most powerful tool available for managing uncertainty in property investment forecasting. Monte Carlo forecasts investment outcomes by sampling uncertain inputs thousands of times, producing a probability distribution of results rather than a single-point estimate. That distribution shows you the range of realistic outcomes, not just the base case.
Typical variables modelled in a property Monte Carlo simulation include:
- Vacancy rates and their year-to-year variability
- Rent growth rates across the hold period
- Exit cap rates at the point of sale
- Capital expenditure timing and cost
- Interest rate movements on variable-rate debt
The output is expressed in percentiles. The 10th percentile result represents a poor outcome. The 50th percentile is the median. The 90th percentile is a strong outcome. Reviewing all three gives you a realistic sense of downside risk, not just the optimistic base case that most pro formas present.
“Scenario and stress testing address ‘what if’ questions critically, improving model reliability beyond base-case reliance.” — Real estate investment analysis framework
Monte Carlo and sensitivity methods reduce false precision by converting a single deterministic IRR into a probability of meeting your return target. That shift from “the IRR is 9.2%” to “there is a 70% chance the IRR exceeds 8%” is far more useful for risk assessment. For baseline analysis, a minimum of 1,000 simulation runs is recommended. Institutional-grade analysis uses 5,000–10,000 iterations to stabilise the output distribution.
6. How to use market data to anchor your forecasting assumptions
Forecasting accuracy depends directly on the quality of your input assumptions. Subjective guesses about vacancy rates or rent growth produce unreliable outputs regardless of how sophisticated the model is. Using market data like vacancy rates and rental growth trends builds more reliable forecasting inputs than estimates made without reference to actual conditions.
Vacancy rate data, for example, is published quarterly by statistical agencies and can be used to calibrate the vacancy assumption in your pro forma. Anchoring inputs to real time-series data makes your assumptions measurable and defensible. It also makes stress testing more meaningful, because you can model scenarios based on historical vacancy peaks rather than arbitrary numbers.
Rental growth assumptions should draw on suburb-level data from sources like CoreLogic or the Australian Bureau of Statistics rather than national averages. Property market trends vary significantly by location, property type, and economic cycle. A forecast built on local data outperforms one built on broad market averages every time.
Pro Tip: Build your portfolio forecasting around a range of vacancy and rent growth scenarios rather than a single assumption. This forces you to confront downside conditions before you commit capital.
7. How to compare and select the right forecasting method
No single method covers every dimension of investment property analysis. The right choice depends on your investment stage, property type, and the specific decision you are trying to make. The table below compares the four core methods across the dimensions that matter most.
| Method | Complexity | Primary output | Best used for |
|---|---|---|---|
| Pro forma modelling | Low to medium | Year-by-year cash flow | Initial screening and deal structuring |
| DCF analysis | Medium | NPV and IRR | Valuation and buy or pass decisions |
| DSCR calculation | Low | Debt coverage ratio | Debt risk and lender underwriting |
| Monte Carlo simulation | High | Probability distribution of returns | Risk assessment and scenario planning |
For investors evaluating a single residential property, pro forma modelling combined with DSCR provides a solid foundation. Add DCF analysis when you need to compare multiple properties or assess whether a purchase price is justified by future cash flows. Monte Carlo simulation becomes worthwhile when the investment is large, the assumptions are uncertain, or the hold period extends beyond five years.
Integrating multiple forecasting methods produces a more complete picture than relying on any one approach. Start with pro forma, apply DCF discounting, check DSCR against your loan terms, and then run Monte Carlo to understand the range of outcomes. Each layer adds a different dimension of insight.
Pro Tip: When comparing two properties, run identical assumptions through both models. Changing inputs between comparisons makes the results meaningless. Consistency in assumptions is what makes comparison valid.
Key takeaways
The most effective investment property forecasting combines pro forma modelling, DCF analysis, DSCR calculation, and Monte Carlo simulation to produce decisions grounded in evidence rather than optimism.
| Point | Details |
|---|---|
| Pro forma is the foundation | Build year-by-year cash flow projections before applying any other forecasting method. |
| DCF converts cash flows to value | Use NPV and IRR to determine whether a purchase price is justified by future returns. |
| DSCR measures debt safety | A DSCR of 1.25x or above indicates sufficient income buffer over mortgage obligations. |
| Monte Carlo manages uncertainty | Run at least 1,000 simulations to convert single-point IRR estimates into probability distributions. |
| Market data anchors assumptions | Use published vacancy and rental growth data to make forecasting inputs defensible and testable. |
Wealthstacker: property forecasting tools for serious investors
Wealthstacker is built for investors who want more than a back-of-envelope calculation. The platform supports pro forma cash flow modelling, automated quarterly property valuations, and personalised wealth projections across both rentvesting and direct ownership strategies.
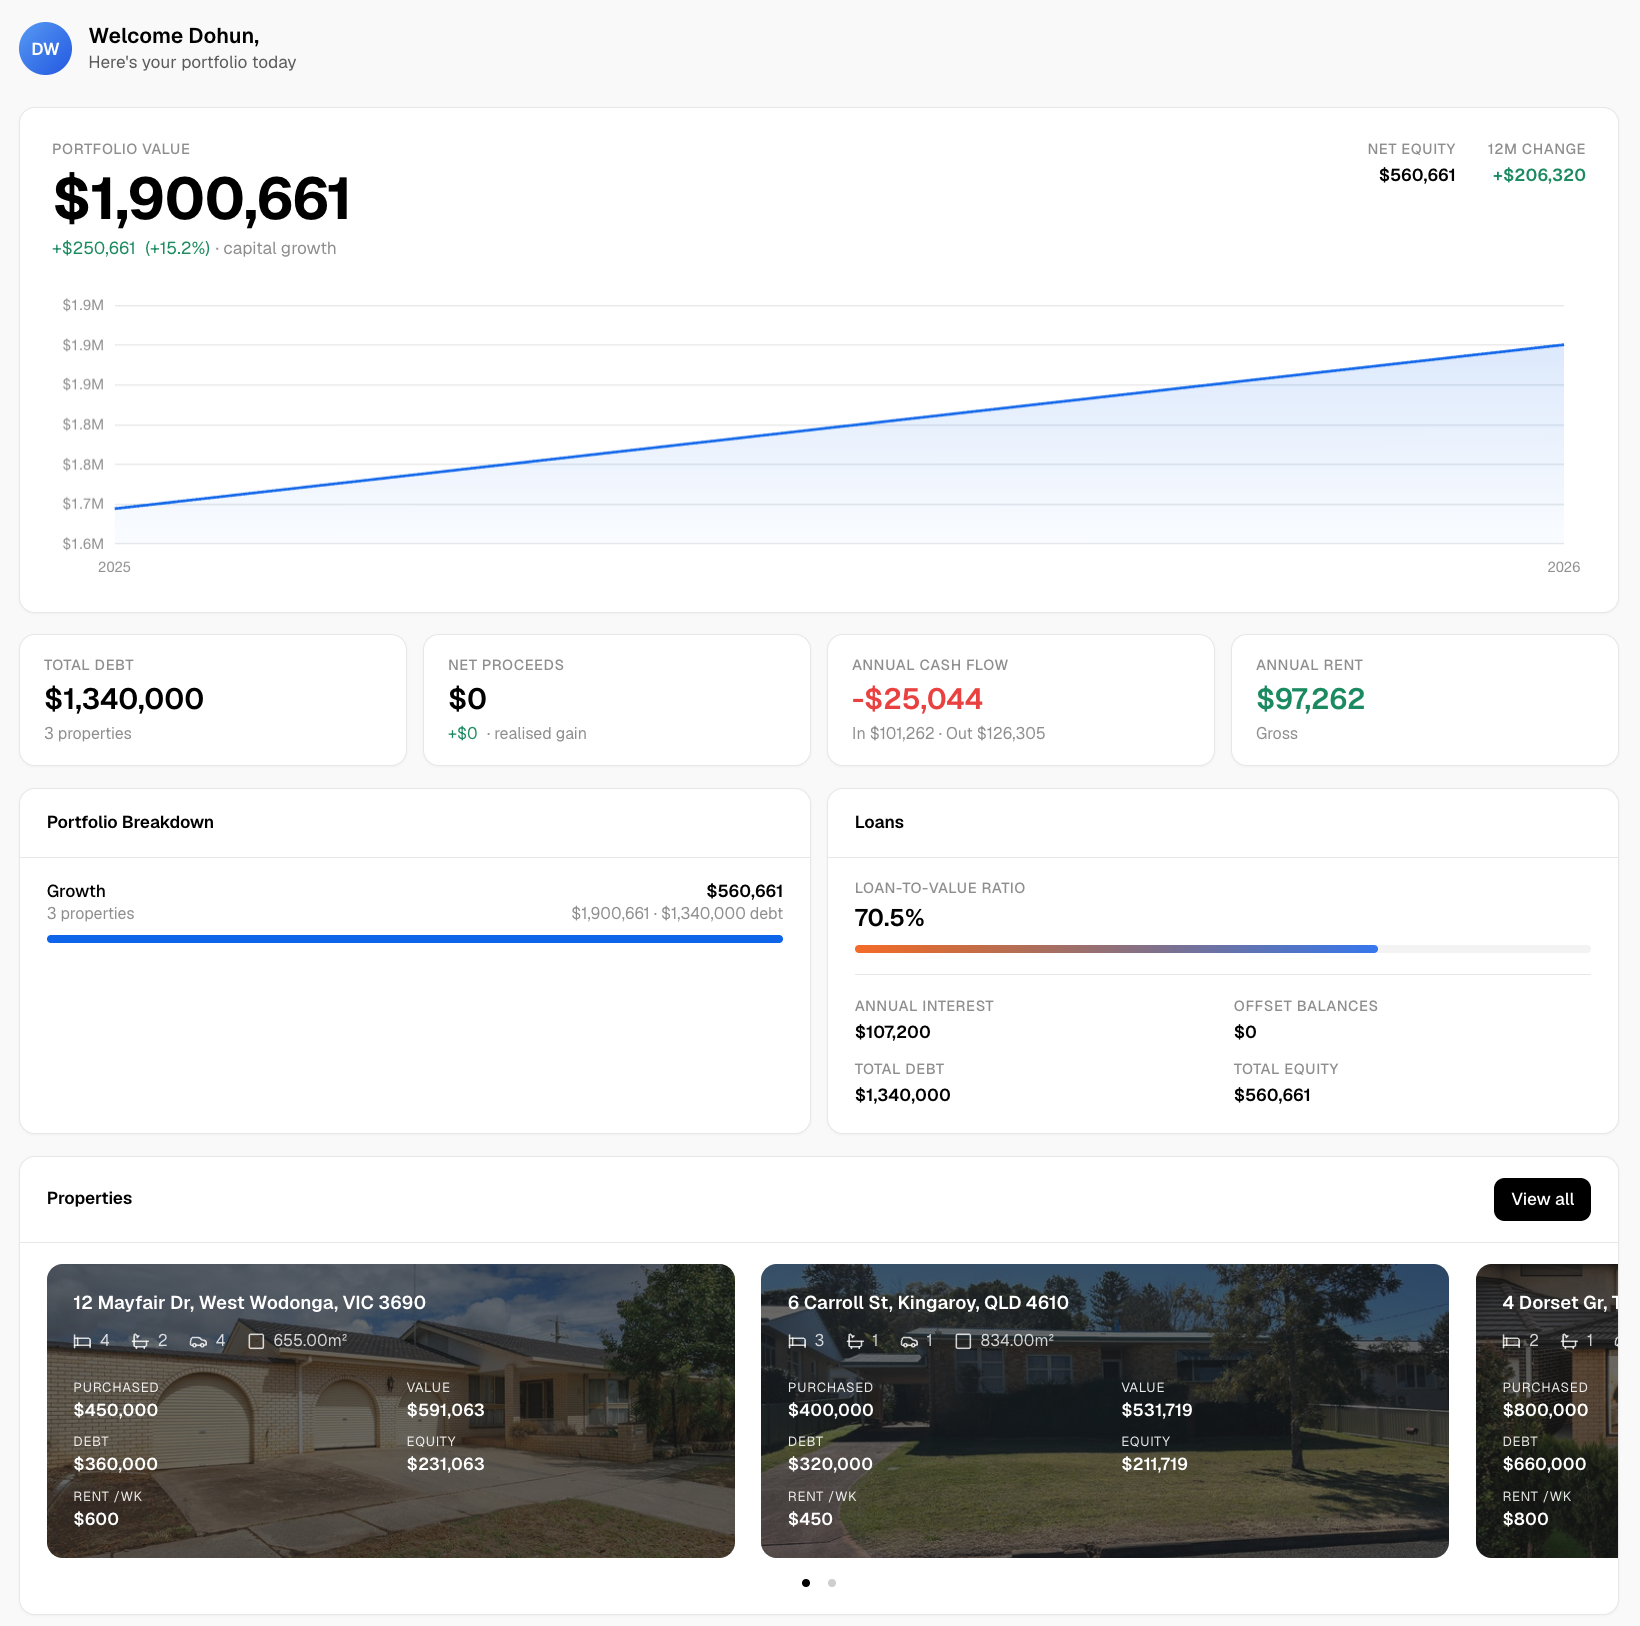
Wealthstacker’s property investment app integrates AI-assisted modelling so you can test multiple scenarios, assess borrowing capacity, and track your portfolio’s projected net worth in real time. For investors who want to apply the forecasting methods covered here without building complex spreadsheets from scratch, Wealthstacker provides the analytical infrastructure to do it. The platform also supports rental yield comparisons and capital growth projections to help you evaluate competing investment strategies side by side.
FAQ
What is pro forma modelling in property investment?
Pro forma modelling is a year-by-year cash flow projection that starts with gross rental income and works down through vacancy, expenses, debt service, and returns metrics like IRR and NPV. It is the foundational step in any serious property investment analysis.
How is DSCR calculated for an investment property?
DSCR is calculated by dividing net operating income by annual debt service. A result of 1.25x or above is the standard benchmark for adequate debt coverage on an investment property.
When should I use Monte Carlo simulation for property forecasting?
Monte Carlo simulation is most useful when your investment horizon exceeds five years, your assumptions carry significant uncertainty, or the deal size justifies institutional-grade risk analysis. A minimum of 1,000 simulation runs is recommended for reliable output distributions.
What is the difference between DCF and direct capitalisation?
DCF projects and discounts cash flows over a multi-year hold period to produce NPV and IRR. Direct capitalisation divides a single year’s NOI by a cap rate to estimate value. DCF is better suited to investments where income is expected to change materially over time.
How do I choose between forecasting methods?
Start with pro forma modelling for initial screening, add DCF for valuation decisions, use DSCR to assess debt risk, and apply Monte Carlo simulation when uncertainty is high or the investment is large. Using all four methods together produces the most complete property investment risk assessment.