High-income earner tax strategies: property in 2026
If you are on the 45% marginal rate, the six property-related tax moves to act on right now are: maximise concessional superannuation contributions before 30 June, secure and document grandfathering evidence for any property purchased before 7:30pm AEST on 12 May 2026, model capital gains tax (CGT) timing ahead of the 1 July 2027 changeover, commission a professional depreciation schedule from a quantity surveyor, assess debt recycling into shares or new builds now that established-property losses face quarantining, and get trust distribution resolutions signed before 30 June.
These six are not arbitrary. Each one has either a hard legislative deadline, a non-cash deduction that costs you nothing in cashflow, or a tax rate delta of up to 30 percentage points. Miss the grandfathering cutoff and you cannot go back. Delay the depreciation schedule and you lose early-year deductions permanently.
Your immediate checklist:
- Pull contracts and settlement records for every property acquired before 12 May 2026 and store them with your tax file.
- Book a meeting with your accountant before 30 June to finalise concessional super contributions and trust resolutions.
- Commission a quantity surveyor depreciation schedule for any investment property that does not already have one.
- Ask your adviser to model three CGT disposal scenarios: before 1 July 2027, after, and phased across both years.
- If you are considering a new residential purchase, confirm whether it qualifies as a new build under the ATO’s negative gearing reform guidance.
At the top marginal tax rates, concessional super contributions are taxed at a lower rate inside the fund, creating a significant tax saving on each dollar contributed, subject to caps and Division 293.
Table of Contents
- How do concessional super contributions reduce your taxable income?
- Negative gearing: what the 2026–27 Budget changes mean for you
- How does depreciation reduce your tax without touching your cash flow?
- Trusts, companies and SMSFs: when do structures actually help?
- CGT planning for property: what changes on 1 July 2027?
- Timing deductions: prepayments, repairs versus improvements
- Does private health insurance actually save you tax?
- What records do you need to protect your tax position?
- What do the 2026–27 Budget reforms mean in practice?
- Key takeaways
- Wealthstacker helps you model what your adviser can only estimate
- Authoritative sources and further reading
How do concessional super contributions reduce your taxable income?
Maximising concessional super contributions is usually the single largest legal tax reducer available to top-bracket earners. The mechanism is straightforward: contributions come out of pre-tax income and are taxed at 15% inside the fund rather than at your marginal rate.
The annual concessional cap includes employer contributions and is subject to official limits each financial year. If your total super balance was below $500,000 on 30 June of the prior financial year, you can carry forward unused concessional cap space from up to five previous years and contribute the accumulated amount in a single year. For someone who has been salary sacrificing modestly for several years, this carry-forward can be substantial.
Worked example: A specialist earning $400,000 who makes a concessional super contribution can save a significant amount in tax compared with receiving that amount as salary due to the difference between marginal tax rates and contributions tax. A catch-up contribution using carry-forward space could save a substantial amount in tax in a single year, subject to the total super balance test.
Division 293 applies an additional tax on concessional contributions for those with income and contributions above a certain threshold, effectively reducing the tax saving for that portion. Still meaningful, but worth modelling precisely before committing to a large catch-up.
Pro Tip: Time large catch-up contributions carefully. Division 293 assessments are issued after lodgement and can create a cash-flow surprise if you have not set aside the liability. Model your Division 293 exposure before 30 June, not after.
Salary sacrifice requires your employer’s agreement and a valid arrangement in place before the income is earned. Check with your super fund that it will accept personal deductible contributions if salary sacrifice is not available through your employer.
Negative gearing: what the 2026–27 Budget changes mean for you
Negative gearing remains available, but its scope for established residential property is narrowing materially. The Treasury Laws Amendment (Tax Reform No. 1) Act 2026 legislates that losses from established residential properties purchased after 7:30pm AEST on 12 May 2026 will be quarantined from 1 July 2027. Those losses cannot offset salary or wages. They can only offset residential property income or be carried forward.
New builds, shares, ETFs, and commercial property are unaffected by the reform. Negative gearing for those asset classes continues as before.
What the three scenarios look like
| Scenario | Purchase timing | Tax treatment from 1 July 2027 |
|---|---|---|
| Grandfathered established property | Before 7:30pm AEST, 12 May 2026 | Losses offset salary/wages as before |
| Established property (post-cutoff) | After 7:30pm AEST, 12 May 2026 | Losses quarantined; offset residential income or carried forward only |
| New build (any timing) | Any date | Full negative gearing retained; losses offset salary/wages |
The cash-flow implications are significant. An established property generating $20,000 in net losses per year currently saves a top-rate earner around $9,000 in tax annually. After 1 July 2027, a post-cutoff purchase produces no immediate salary offset. That $9,000 annual saving disappears until the investor has sufficient residential property income to absorb the loss.
What to stress-test before any purchase:
- Model the property’s cash flow assuming no tax offset from losses (worst case for post-cutoff established stock).
- Run interest rate sensitivity at +2% and +3% above current rates.
- Test vacancy at 8–10 weeks per year.
- Confirm whether the property qualifies as a new build under ATO guidance.
Practitioner guidance is clear on this point: tax benefits should not be the primary reason to buy a property that fails on cash-flow or growth grounds. If the investment only stacks up because of the tax offset, the 2026 reforms have changed the equation for established stock bought after the cutoff.
Debt recycling into a diversified share portfolio has become structurally more attractive for many high earners precisely because negative gearing for shares remains intact while established-property losses face quarantining for new purchases.
How does depreciation reduce your tax without touching your cash flow?
Depreciation is the most underused deduction in property investing. It costs you nothing in cash and can generate substantial reductions in taxable income, particularly in the first five to seven years of ownership.
Two divisions govern it. Division 40 covers plant and equipment: carpets, blinds, dishwashers, air-conditioning units, hot water systems. These items depreciate at varying rates depending on their effective life as set by the ATO. Division 43 covers capital works: the structural elements of the building itself, typically deducted at 2.5% per year over 40 years for residential properties built after 1987.
Depreciation schedules commonly deliver $8,000–$20,000 per year for new properties in early years, and the cost of the quantity surveyor’s report is itself deductible. For a top-rate earner, a $15,000 annual depreciation deduction is worth around $6,750 in tax saved, every year, with no cash outlay.
Commission a professional depreciation schedule from a registered quantity surveyor promptly after settlement. The ATO requires a quantity surveyor’s report for properties where you did not build or purchase new, and even for new builds the schedule ensures you capture every eligible item.
Commonly overlooked deductible items:
- Property management fees and letting fees
- Council rates and water charges
- Landlord insurance premiums
- Strata levies (where applicable)
- Loan establishment fees (amortised over the loan term)
- Pest and building inspection costs at purchase
- Depreciation on assets installed during renovations
Pro Tip: If you purchased a property in the last three years and have not yet commissioned a depreciation schedule, you can generally amend prior-year returns to capture missed deductions. Ask your accountant whether an amendment is worthwhile before the statute of limitations closes.
For a practical breakdown of allowable non-cash deductions including Division 40 and Division 43, the AeroWealth guide is a useful complementary reference.
Trusts, companies and SMSFs: when do structures actually help?
Structures can deliver real tax and asset-protection benefits, but they must have genuine commercial purpose. The ATO scrutinises arrangements that exist primarily to shift income to lower-rate taxpayers without a legitimate non-tax reason.
The four main options for property investors are individual ownership, discretionary (family) trust, company, and self-managed superannuation fund (SMSF). Each produces different outcomes for property income, capital gains, and compliance cost.
| Structure | CGT discount access | Tax rate on income | Distribution flexibility | Borrowing implications |
|---|---|---|---|---|
| Individual | 50% (pre-1 July 2027) | Marginal rate (up to 45%) | None | Standard residential lending |
| Discretionary trust | Yes (flows to beneficiaries) | Beneficiary’s marginal rate | High | Lender-specific; often higher rates |
| Company | No 50% discount | — | Low (dividends) | Standard commercial terms |
| SMSF | 10% in accumulation; 0% in pension | 15% accumulation / 0% pension | Restricted | Limited recourse borrowing only |
The discretionary trust is the most flexible for income splitting, but Section 100A of the Income Tax Assessment Act 1936 is an active ATO focus. Distributions to adult children or other low-rate beneficiaries must reflect genuine entitlements and cannot be part of an arrangement where the economic benefit flows back to the high-rate taxpayer. Trustee resolutions must be signed and dated before 30 June each year.
SMSFs can hold property at a 15% tax rate in accumulation phase and 0% in pension phase, which is compelling for long-term holds. The catch is that the property cannot be acquired from a related party (with limited exceptions for business real property) and cannot be lived in or rented to related parties.
Structures are not a shortcut. The ATO’s Section 100A guidance and the general anti-avoidance provisions in Part IVA mean that arrangements lacking commercial substance face reconstruction. The question to ask your adviser is not “which structure saves the most tax?” but “which structure makes sense for this investment on its own commercial merits, and what tax outcome does that produce?”
For passive property investment strategies that integrate trusts and super with broader portfolio planning, Wealthstacker’s blog covers the structural trade-offs in detail.
CGT planning for property: what changes on 1 July 2027?
Timing a disposal can change your tax bill by hundreds of thousands of dollars. Two levers matter most right now: the 12-month holding rule and the 1 July 2027 CGT changeover.
Under current law, assets held for more than 12 months by individuals, trusts, and partnerships attract a 50% CGT discount. From 1 July 2027, the Treasury Laws Amendment (Tax Reform No. 1) Act 2026 replaces that discount with cost base indexation and a 30% minimum tax on gains arising after that date. Gains that accrued before 1 July 2027 may be eligible for transitional treatment, but the precise mechanics depend on your specific circumstances and the ATO’s implementation guidance.
| Action | Timing | Why it matters |
|---|---|---|
| Review embedded gains on all properties | Now | Quantify exposure before the changeover |
| Obtain independent market valuations | Before 1 July 2027 | Establishes pre-changeover value for transitional purposes |
| Model phased disposals | Before 30 June 2027 | Spread gains across tax years to manage marginal rate impact |
| Coordinate with trust distributions | Before 30 June each year | Ensure CGT discount flows to the right beneficiary |
| Confirm contract and settlement dates | At purchase and sale | Evidence for ATO on which CGT regime applies |
Pro Tip: A property with a large embedded gain that you were planning to hold for another decade may now warrant a different decision. Run the numbers on disposing before 1 July 2027 versus holding under the new regime. The difference is not always in favour of selling early, but you need the model to know.
The main residence exemption remains available for your primary home, subject to the usual conditions. If you have been renting out part of your home or have had periods of non-residence, get a specific ruling from your accountant on the partial exemption calculation before any sale.
Timing deductions: prepayments, repairs versus improvements
Prepaying allowable expenses and correctly classifying repairs can reduce taxable income in a target year. The rule is simple: expenses incurred in the income year are deductible in that year, subject to the prepayment rules.
For investment property loans, you can generally prepay up to 12 months of interest in advance and claim the deduction in the year of payment, provided the prepayment period does not extend beyond 12 months from the date of payment. This is a legitimate timing tool, not a loophole, and the ATO’s rental expense guidance confirms it.
The repairs versus improvements distinction trips up many investors. A repair restores an asset to its original condition and is deductible immediately. An improvement adds new functionality or extends the asset’s useful life and must be depreciated over time. Replacing a broken hot water system with an equivalent unit is a repair. Replacing a single-zone system with a ducted multi-zone system is an improvement.
End-of-year checklist for high earners:
- Prepay loan interest where your lender allows and the period does not exceed 12 months.
- Finalise and sign trust distribution resolutions before 30 June.
- Commission or update your depreciation schedule if you have made improvements during the year.
- Obtain market valuations for properties where you are considering a disposal.
- Confirm your concessional super contributions are received by the fund before 30 June.
Pro Tip: Do not prepay expenses across multiple properties in the same year without modelling the aggregate taxable income impact. Prepayments reduce income in year one but create a gap in year two. If your income is likely to be lower next year, the timing benefit may be smaller than it appears.
Does private health insurance actually save you tax?
For many high earners, private hospital cover is not just a health decision. It is a tax one. The Medicare Levy Surcharge (MLS) applies to singles with taxable income above $93,000 and families above $186,000 who do not hold an appropriate level of private hospital cover.
The MLS rates are tiered. For singles, the surcharge is 1% on income between $93,001 and $108,000, 1.25% between $108,001 and $144,000, and 1.5% above $144,000. At $300,000 in taxable income, the MLS exposure without private cover is $4,500 per year. A basic private hospital policy typically costs less than that, making the cover financially self-funding for most top-rate earners.
Key points on MLS compliance:
- Cover must be held for the full income year to avoid the surcharge; partial-year cover results in a proportional surcharge.
- The family threshold applies when combined family income exceeds $186,000, regardless of how income is split between partners.
- The MLS is calculated on taxable income, reportable fringe benefits, and total net investment losses, not just salary.
- Check your policy’s hospital cover tier: extras-only cover does not avoid the MLS.
The MLS interacts directly with income-splitting decisions. If trust distributions or salary sacrifice reduce your taxable income below the relevant threshold, the surcharge may not apply. Model the combined household position, not just your individual income, before making cover decisions.
For current threshold figures, the ATO’s MLS information is the primary reference.
What records do you need to protect your tax position?
Good records save your tax position. The documents your adviser will ask for when the ATO comes knocking are specific, and assembling them now is far easier than reconstructing them under pressure.
Documents to assemble immediately:
- Signed contracts of sale with timestamps for all properties, particularly those acquired before 7:30pm AEST on 12 May 2026.
- Settlement statements and transfer documents confirming settlement dates.
- Quantity surveyor depreciation schedules for each investment property.
- Loan documents, including original facility agreements and any refinancing records.
- Trust deeds and all signed trustee resolutions, dated before 30 June for each relevant year.
- Rental income records and property management statements.
- Receipts for all claimed deductions, including repairs, insurance, and rates.
For grandfathering purposes, the contract timestamp is the critical evidence. If your contract was exchanged before 7:30pm AEST on 12 May 2026, that property retains full negative gearing treatment regardless of when settlement occurred. Keep the original signed contract, the agent’s confirmation of exchange time, and any solicitor correspondence confirming the exchange timestamp.
Escalate to a specialist tax lawyer when you are dealing with related-party transactions, complex trust restructures, or any arrangement that a reasonable person might describe as primarily tax-motivated. A property tax accountant handles the annual compliance; a tax lawyer handles disputes, restructures, and private rulings.
Pro Tip: Request a private ruling from the ATO before entering any arrangement you are uncertain about. A ruling is binding on the ATO for your specific facts and provides certainty that no amount of general advice can replicate.
Review your position with an adviser at least quarterly during years of significant change, and model annually as a baseline. If you are planning a new acquisition that hinges on negative gearing treatment, model before you sign, not after.
What do the 2026–27 Budget reforms mean in practice?
The policy inputs for this guide draw from ATO guidance and the Treasury Laws Amendment (Tax Reform No. 1) Act 2026, which is the primary legislative source for both the negative gearing quarantining rules and the CGT changeover.
The three most consequential reform points for property investors are:
- Quarantining of losses from established residential property purchased after 7:30pm AEST on 12 May 2026, effective 1 July 2027. Losses can only offset residential property income or be carried forward.
- New-build carve-out: negative gearing for new residential builds remains fully intact, creating a structural preference for new supply over established stock for investors buying after the cutoff.
- CGT changeover on 1 July 2027: the 50% discount is replaced by cost base indexation and a 30% minimum tax on gains arising after that date.
Division 296, which commenced 1 July 2026, applies an additional tax on earnings within very large superannuation balances. If your total super balance is approaching the relevant threshold, model the Division 296 exposure alongside your concessional contribution strategy.
Practical modelling outputs to produce with your adviser include: a 15-year cash-flow projection under three interest rate scenarios, a CGT outcome table comparing disposal before and after 1 July 2027, and a tax-paid sensitivity analysis showing how vacancy and rate changes affect net returns.
Pro Tip: The investment property forecasting methods that matter most are those that stress-test your position under adverse assumptions, not optimistic ones. A model that only works at current rates and full occupancy is not a model; it is a hope.
Wealthstacker’s 15-year projection tools and scenario modelling features are designed to produce exactly these outputs, including rentvesting comparisons and depreciation inputs that reflect the post-reform environment.
Key takeaways
High-income Australian property investors who act on grandfathering evidence, concessional super contributions, and CGT timing before 1 July 2027 will preserve the largest legally available tax benefits under the 2026–27 Budget reforms.
| Point | Details |
|---|---|
| Grandfathering is time-critical | Secure and store contracts dated before 7:30pm AEST, 12 May 2026 to preserve full negative gearing treatment. |
| Super contributions save up to ~30 percentage points | Maximise concessional contributions and carry-forward space before 30 June each year. |
| CGT changeover is 1 July 2027 | Model disposal timing now; the 50% discount is replaced by cost base indexation and a 30% minimum tax after that date. |
| Depreciation costs nothing in cash | Commission a quantity surveyor schedule promptly; it typically delivers $8,000–$20,000 p.a. in non-cash deductions for new properties. |
| Wealthstacker for scenario modelling | Use Wealthstacker’s 15-year projection and rentvesting tools to stress-test tax outcomes before committing to any purchase or disposal. |
Wealthstacker helps you model what your adviser can only estimate
Running the numbers on a property tax strategy without a modelling tool is like navigating without a map. You know the direction, but you cannot see the terrain.
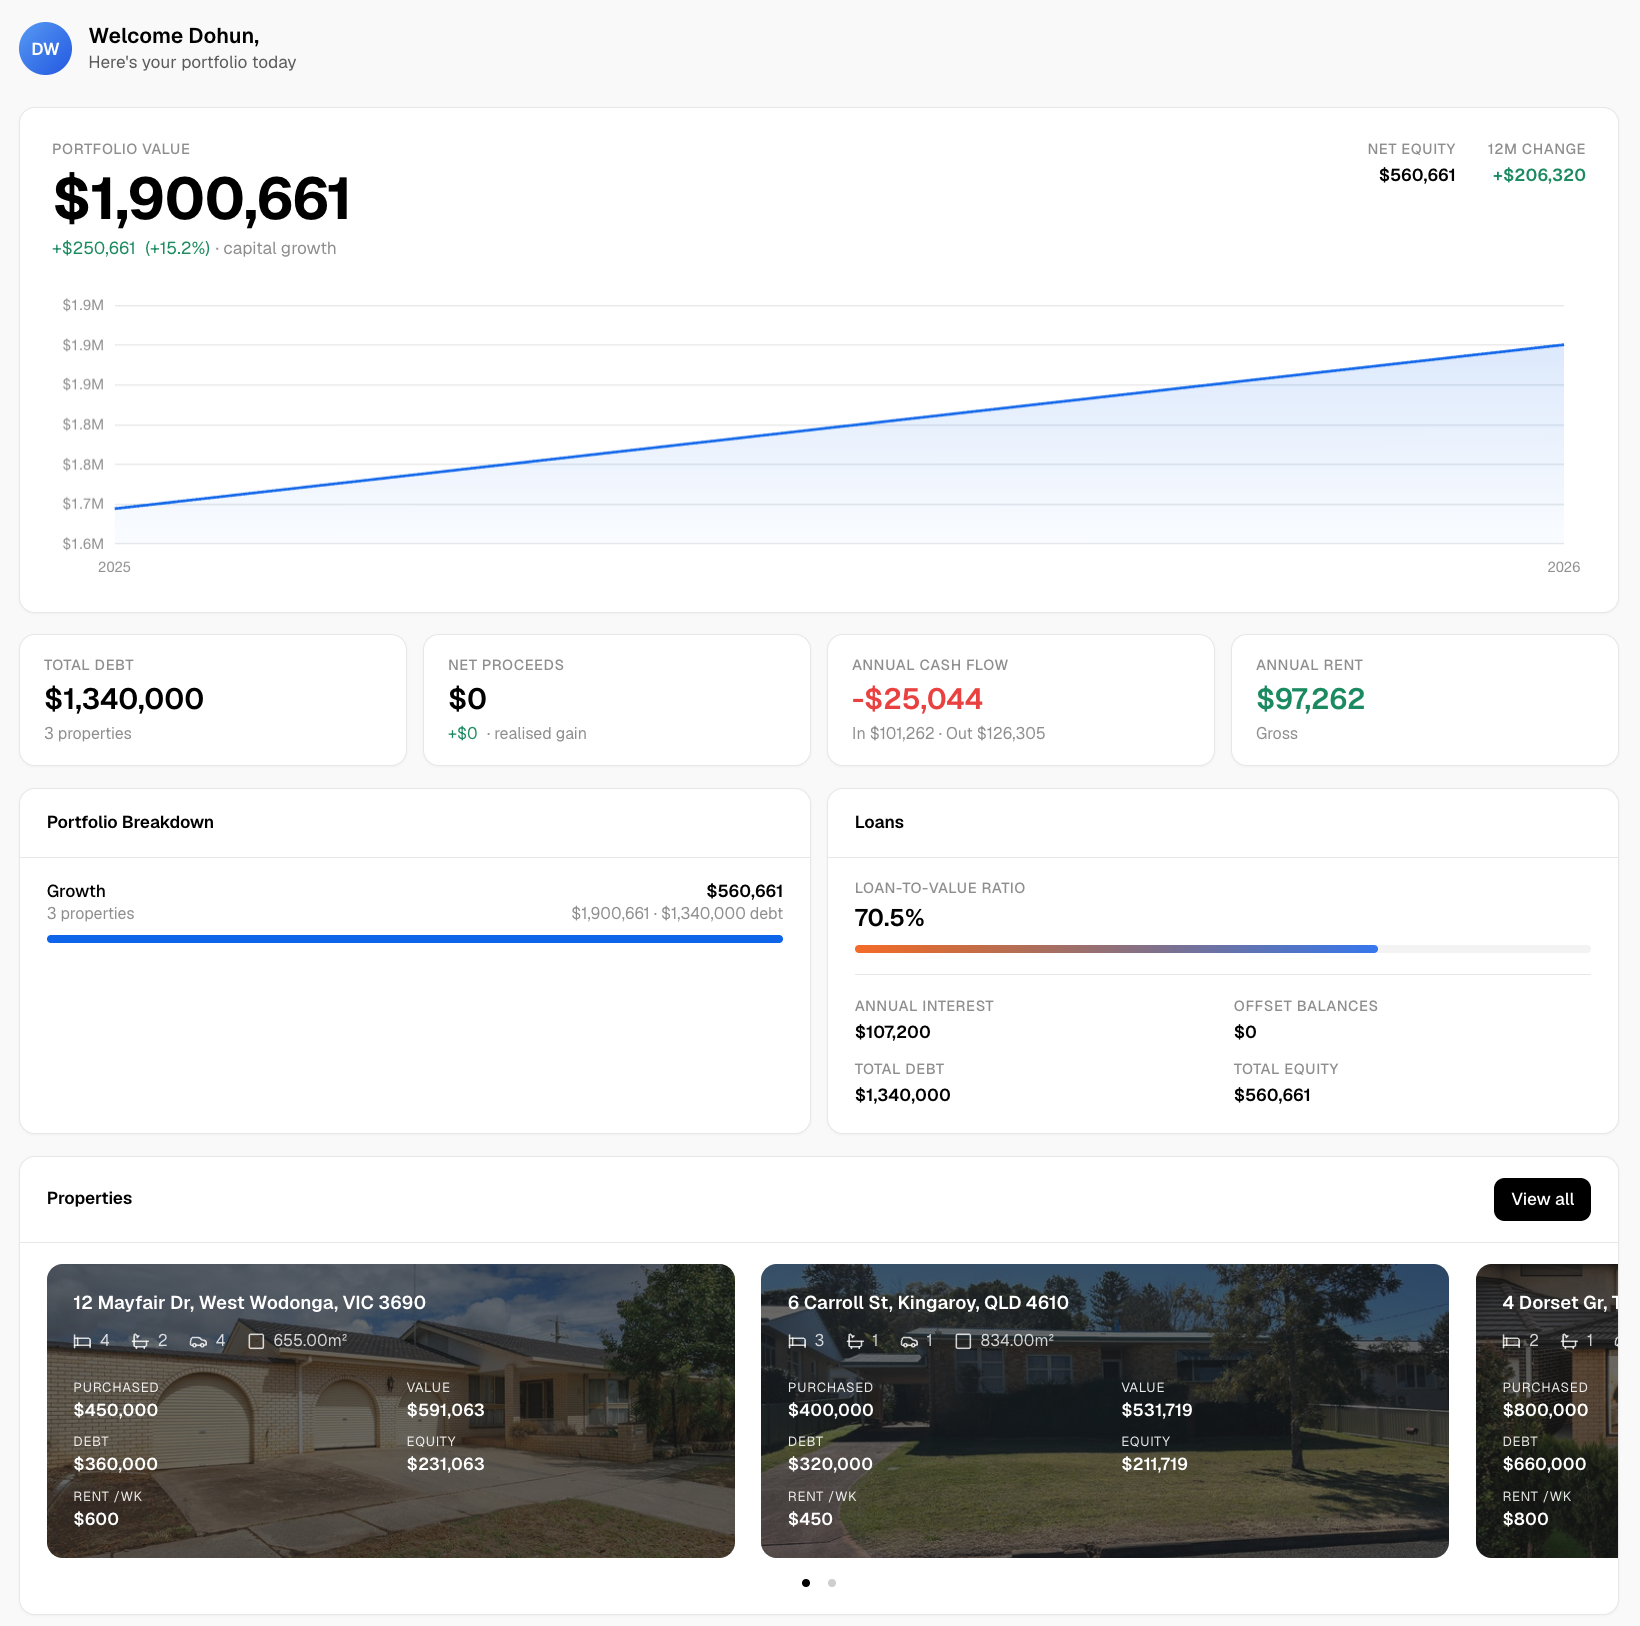
Wealthstacker gives high-income investors a concrete advantage: free automated quarterly property valuations, a portfolio tracking dashboard, and 15-year investment projections that let you test the scenarios this guide describes, including rentvesting comparisons, depreciation inputs, and CGT timing outcomes under different disposal assumptions. The property investment app is built for exactly the kind of stress-testing your adviser will recommend: interest rate shocks, vacancy sensitivity, and post-1 July 2027 CGT treatment side by side.
Every modelling example in this guide, from the concessional super worked example to the three negative gearing scenarios, can be reproduced and extended in the platform. Sign up for the free dashboard, run your current portfolio through the valuation and projection tools, and bring the outputs to your next adviser meeting. That conversation will be sharper, faster, and more specific to your actual numbers.
Authoritative sources and further reading
The legislative and regulatory foundation for this guide comes from primary government sources. Readers and advisers should verify current rules directly.
Primary sources:
- Treasury Laws Amendment (Tax Reform No. 1) Bill 2026, Parliament of Australia: the full legislative text covering negative gearing quarantining (Schedule 2) and CGT changeover (Schedule 1).
- ATO: Tax reform — boosting home ownership, reforming negative gearing and capital gains tax: ATO’s practical guidance on the reforms, grandfathering rules, and new-build carve-out.
- ATO: How to claim rental expenses: definitive guidance on deductible rental expense categories, prepayment rules, and capital works.
- Budget 2026–27: Tax reform: Treasury’s summary of the policy intent and key dates.
Industry and practitioner guidance:
- Real Homes Realty: Investment property tax deductions Australia (2026): practical checklist of deductible items and depreciation schedule guidance.
- AeroWealth: Tax write-off investment property — your 2026 Australian guide: worked examples of Division 40 and Division 43 deductions.
Keep copies of all contracts, settlement statements, quantity surveyor reports, and trustee resolutions in a dedicated tax file. The ATO’s standard amendment period is two years for most individuals, but complex arrangements involving trusts or related parties can attract a four-year review window. Documents you cannot produce are deductions you cannot defend.
This article provides general information only and does not constitute financial, tax, or legal advice. Tax laws change frequently and individual circumstances vary. Confirm your specific position with a registered tax agent, financial adviser, or solicitor before acting on any strategy described here.