
Avoid Insolvency: Size Your Australian Cash Buffer with Recovery Time
Aim for a cash flow buffer equivalent to a few months of operating costs as a baseline, increasing the duration if your business is seasonal or higher risk. Build the figure using one of two methods: a fixed-months approach, or a burn-rate plus recovery-time calculation. If your current reserve falls short of either, update your forecast and get advice before the gap becomes a crisis.
TL;DR:
- Business owners should set a cash buffer to cover at least one to three months of operating costs, or more for seasonal or high-risk sectors.
- A simple fixed-months approach works for stable businesses, while burn-rate and recovery-time calculations suit volatile or seasonal operations better.
- The buffer should include fixed costs, variable or seasonal expenses, and lump-sum obligations like tax and super payments, which are best kept in dedicated accounts.
- Maintaining the buffer in a separate account and automating transfers help prevent casual spend and ensure quick access when needed.
- Regularly reviewing and recalculating the buffer every quarter, based on current costs, risks, and industry factors, improves preparedness for cash flow dips.
WealthstackerModel Your Wealth StrategyWealthStacker helps you compare rentvesting and buying strategies with real-time net worth modelling and tailored forecasts.Visit WealthStacker
Table of Contents
- What a cash buffer is and why it matters for business survival
- How to calculate the right buffer for your business
- What to include in the cash buffer calculation
- Where to keep the buffer and how to structure your accounts
- How to build the buffer without disrupting operations
- Warning signs your buffer is under stress
- Maintain and review: cadence, triggers and a sample checklist
- Impact of buffer size on business creditworthiness and borrowing capacity
- Adjusting buffer amounts for seasonal or industry-specific fluctuations
- Tax implications of maintaining and using a cash flow buffer
- Buffer strategies across different business sizes and sectors
- Model your buffer and recovery scenarios with WealthStacker
- FAQ
- Sources
What a cash buffer is and why it matters for business survival
A cash flow buffer is the cash you deliberately hold aside, separate from day-to-day operating funds, so you can keep paying wages, suppliers and tax obligations even when revenue stalls or a big bill lands early. It is not the same as working capital, which covers the normal gap between paying for stock or labour and collecting payment from customers. It is also not the same as an overdraft or line of credit, which is borrowed money you pay interest on and which can be reduced or withdrawn by the lender at short notice.
The distinction matters because of how insolvency is tested in Australia. ASIC applies a cash-flow test to determine whether a company is trading while insolvent: the question is whether the business can pay its debts as and when they fall due, not whether it holds valuable assets on paper. A business can own property, equipment and a full order book and still be insolvent if it cannot meet payroll or a tax bill on the due date. Directors who keep trading once that line is crossed risk personal liability, which is why a buffer is as much a governance tool as a financial one.
Insolvency is the inability to pay debts as and when they fall due, and directors who fail to act early face personal risk.
A properly sized buffer protects three things in practice: payroll runs so staff are never paid late, statutory obligations like BAS, GST and superannuation so you avoid penalties and ATO attention, and supplier relationships so you keep the trading terms and goodwill that let a business recover from a rough quarter. Without it, a single slow-paying client or an unexpected repair bill can cascade into missed obligations within weeks.
How to calculate the right buffer for your business
There is no single correct number because the right buffer depends on how volatile your revenue is, how exposed you are to lumpy statutory payments, and how quickly you could realistically recover if income stopped. Three calculation approaches cover most situations, and most businesses end up blending them.
Fixed-months approach. This is the simplest method: multiply your average monthly operating costs by a chosen number of months. A stable, low-risk service business with predictable contracts might aim for a short buffer target. A business with more revenue volatility, a single large client, or exposure to a seasonal market might set a longer target. A business in a high-risk sector, such as construction or hospitality, or one still building a track record, might consider an even longer buffer. The method is easy to communicate to a bookkeeper or lender, but it treats every business the same regardless of how fast cash actually drains.
Burn-rate plus recovery-time method. This is the more precise approach and the one favoured in formal treatments of reserve sizing, which recommend basing buffer size on cash-flow volatility, forecast error and how exposed the business is to funding or refinancing risk, as set out in IMF research on setting up a cash buffer. The steps are:
- Calculate net monthly cash burn: total cash outflows minus total cash inflows in a typical month, or in a bad month if you want a conservative figure.
- Estimate your realistic recovery time: how many months it would take to restore normal income if a key client left, a season ended, or demand dropped sharply.
- Multiply burn rate by recovery time to get your target buffer.
- Add a margin, commonly 10 to 20%, to absorb forecast error.
Practitioners favour this method precisely because it captures both how fast cash is disappearing and how long it realistically takes to fix that, rather than applying the same multiple to every business regardless of its risk profile.
Obligations-first ring-fence. Whichever headline method you use, ASIC’s guidance for directors points to a two-part structure as the most resilient option: a ring-fenced amount that covers GST, PAYG withholding, superannuation and loan repayments, held separately from an operational buffer sized by burn-rate times recovery time. This stops a quarterly BAS bill or a super payment from instantly wiping out the cash you were counting on for payroll.

Worked example one, a small café. Average monthly operating costs are $40,000. Using the fixed-months approach at three months, the target buffer is $120,000. The obligations-first component, covering quarterly GST and super, might add a further $18,000 ring-fenced separately.
Worked example two, a two-person consultancy. Monthly costs are $12,000, almost all fixed (rent, software, one salary). A 90-day fixed buffer is $36,000. Burn rate in a no-new-client month is close to the full $12,000, and recovery time for a services business with a short sales cycle might be two months, giving a target of $24,000 plus margin, around $27,600. Because fixed costs dominate, the fixed-months figure is the more conservative and sensible choice here.
Worked example three, a seasonal landscaping business. Monthly costs average $25,000 but swing heavily with season. Burn rate in the off-season, when revenue drops to near zero, is close to $22,000 a month, and recovery time to the next busy season might be five months, giving a target of $110,000 plus margin, around $126,500, well above a flat three-month figure of $75,000. This is the clearest case for the burn-rate method over a fixed multiple.
Decision checklist:
- If your revenue is stable and predictable month to month, start with the fixed-months approach at 90 days.
- If your revenue is volatile, seasonal, or concentrated in a few clients, use burn-rate times recovery time instead.
- Always add the obligations-first ring-fence on top of either method, never folded into it.
- Recalculate whenever your cost base, staffing or client concentration changes materially.
What to include in the cash buffer calculation
A buffer that only accounts for rent and wages will be hollowed out the moment a quarterly tax bill or an annual insurance renewal lands. Build your figure from three categories of cost rather than guessing at a round number.
- Fixed costs, which recur every month regardless of trading volume: rent, insurance premiums, loan or lease repayments, utilities and software subscriptions.
- Variable and seasonal costs, which move with trading activity: wages and casual labour, cost of goods sold, and supplier payments tied to order volume.
- Periodic or lumpy liabilities, which arrive less often but in large amounts: GST and BAS payments, PAYG withholding, and superannuation contributions.
The periodic category deserves particular attention because the timing itself is changing. The ATO has confirmed that from 1 July 2026, a payday-frequency change to superannuation payment rules will affect how often employers need to remit contributions, which shifts the cash flow timing employers need to plan around rather than treating super as a quarterly-only event. Businesses that have always budgeted super as a lump sum four times a year will need to revisit that assumption.
It is tempting, when cash is tight, to reach for a personal credit card or a short-term personal loan to cover a gap rather than draw down the buffer. This is risky for two reasons: the interest cost is usually far higher than any return you are protecting, and it blurs the line between business and personal liability, which can complicate both your tax position and your personal exposure if the business later struggles. The safer practice, recommended in ATO and business.gov.au cash flow guidance, is to set aside tax and super amounts in a separate account as they accrue, so the money is never available to be accidentally spent on operating costs in the first place.
Pro Tip: Open a dedicated “tax and super” sub-account and transfer the relevant percentage of every invoice paid on the day it lands, rather than waiting until BAS time to work out what you owe.
Where to keep the buffer and how to structure your accounts
Holding your buffer in the same account as everyday operating cash creates what behavioural finance calls the availability illusion: if the money is visible and accessible, it tends to get spent on whatever feels urgent that week, regardless of what you intended it for. A separate account, even at the same bank, creates enough friction to protect the reserve from casual erosion.
Three practical placement options suit most small and medium businesses:
- A separate business savings account gives same-day or next-day access with no lock-in, suiting the obligations-first component you may need at short notice.
- A short-term term deposit, laddered across one, three and six-month terms, can earn a better return on the portion of the buffer you are confident you will not need immediately.
- A sweep account, which automatically moves surplus cash from your transaction account into a higher-interest holding account overnight, suits businesses that want the buffer to build passively without manual transfers.
Whichever structure you choose, match the liquidity of each portion to when you expect to need it. Locking the component earmarked for next month’s PAYG payment into a 90-day term deposit defeats the purpose of having it. A sensible split keeps the obligations-first ring-fence fully liquid and allows only the longer-dated operational buffer to sit in anything less accessible.
Access controls matter as much as placement. Require two signatories or a documented sign-off step before funds move out of the reserve account, even if that feels like unnecessary friction for a two-person business. That small barrier is often the only thing standing between a buffer and a tempting short-term spend that seemed justified in the moment.
How to build the buffer without disrupting operations
Most businesses do not have a spare lump sum sitting around to drop into a new reserve account, so building the buffer is a staged process rather than a single transfer.
Start with operational moves that free up cash without new borrowing: cut discretionary spend that is not driving revenue, renegotiate supplier payment terms where you have the leverage to do so, and tighten invoicing so money is requested the day work is completed rather than at the end of the month. Business frames this as the first step before any forecast can be trusted: get a clear, current picture of what is actually coming in and going out.
- Allocate a fixed percentage of every receipt, commonly 5 to 15%, to automatically transfer into the reserve account the day it is received.
- Automate the transfer through your banking or accounting software so the saving happens without a manual decision each time.
- Track buffer coverage in days (buffer balance divided by average daily operating cost) as your core KPI, and review it monthly until you reach your target.
- If the target is urgent, consider temporarily reducing owner drawings rather than borrowing, since this preserves equity and avoids interest cost.
Borrowing to build a buffer faster, through a business loan or invoice finance, is occasionally appropriate when a large receivable is tied up and the cost of finance is clearly lower than the cost of missing a payroll or tax deadline. It should be the exception, not the default, because debt-funded reserves still carry repayment obligations that reduce the buffer’s real protective value.
Pro Tip: Track “buffer coverage days” alongside your usual profit and loss figures. It turns an abstract savings goal into a number you can watch improve week by week.
Warning signs your buffer is under stress
Certain patterns tend to show up well before a cash crisis becomes visible on the bank statement, and recognising them early gives you more options.
- Juggling which creditor to pay first, or delaying one supplier to pay another.
- Superannuation or PAYG payments that are overdue or repeatedly paid late.
- Relying on an overdraft or credit facility every month rather than occasionally.
- Receiving calls from suppliers chasing payment rather than you initiating contact.
If any of these are happening, the immediate steps are to update your cash flow forecast with current numbers, pause discretionary spend, and contact your accountant or a service such as the Small Business Debt Helpline before the gap widens further.
ASIC’s guidance for businesses in financial difficulty is explicit that early action increases your options and that waiting increases a director’s personal exposure. ASIC’s safe-harbour provisions can, in some circumstances, protect directors who are developing a genuine restructuring plan while continuing to trade, but qualifying for that protection depends on acting early and keeping proper records, not on hoping the situation resolves itself.
Early engagement with an accountant or a debt-help service preserves options; waiting to act increases the risk of personal liability for directors, according to ASIC’s guidance for small business directors.
Keep dated records of every decision made during a cash squeeze, including forecasts reviewed and advice sought. That paper trail matters if you ever need to demonstrate you acted on the information available at the time.
Maintain and review: cadence, triggers and a sample checklist
A buffer calculated once and never revisited drifts out of date within a couple of quarters as costs, staffing and client mix change. Build review into a routine rather than treating it as an annual exercise.
- Reconcile actual cash position against forecast weekly, since this is the single habit most likely to catch a developing problem early.
- Run a rolling 13-week cash flow forecast, updated weekly, to see short-term pressure points before they arrive.
- Conduct a quarterly strategy check that revisits your buffer target against current operating costs and recent revenue volatility.
- Monitor aged receivables alongside the forecast, since slow-paying customers are one of the most common causes of a buffer being drawn down unexpectedly.
Set explicit trigger thresholds rather than relying on a general sense that things feel tight. A common approach is to trigger a response when buffer coverage drops below 30 days, or when aged receivables over 60 days exceed a set proportion of outstanding invoices.
A short checklist to run at each review:
- Is the buffer balance at or above target coverage days?
- Are upcoming tax, super and loan dates mapped against the 13-week forecast?
- Are aged receivables within normal range, or is a customer dragging on payment terms?
- Has anything changed in cost base, staffing or client concentration that should shift the target?
Business.gov.au’s cash flow statement tool provides a template that supports this kind of regular reconciliation without building a forecasting system from scratch.
Impact of buffer size on business creditworthiness and borrowing capacity
A healthy cash buffer is one of the clearer signals a lender looks for when assessing a business loan or a facility extension, because it demonstrates the business can absorb a shock without missing a repayment. Lenders typically review recent bank statements and cash flow history as part of an application, and a business that shows consistent reserve levels and rarely dips into an overdraft presents a materially lower risk profile than one that runs close to zero every month.
The relationship works in both directions. A stronger buffer can support a better borrowing rate or a larger approved facility, while a thin or volatile cash position can see an application declined even when the underlying business is profitable on paper, since profit and cash availability are not the same thing. Businesses applying for finance to expand, or seeking to refinance an existing facility, are generally better placed doing so from a position of visible reserve strength rather than while rebuilding a depleted one.
This is also where the obligations-first component pays off beyond its immediate purpose: a business that can show tax and super are consistently set aside and paid on time, rather than scrambled together at deadline, reads as lower risk to a lender assessing repayment reliability.
Adjusting buffer amounts for seasonal or industry-specific fluctuations
A flat buffer target applied uniformly across the year under-protects a seasonal business during its low months and over-allocates cash during its peak. A landscaping, tourism or retail business with a defined off-season should size its buffer around the burn-rate and recovery-time method rather than a flat multiple of average costs, since average costs smooth over the exact period when the business is most exposed.
The practical adjustment is to calculate burn rate using the worst typical month, not the annual average, and to set recovery time based on how long the gap to the next peak season genuinely runs. A ski-season business with a five-month off-peak period needs a buffer sized to survive those five months, not a fraction of its annual cost base.
Industry exposure matters too. Construction and hospitality carry higher structural volatility from project timing and discretionary consumer spend, and both sit toward the higher end of the one to twelve month range for that reason. A professional services business with retainer clients and predictable monthly billing can usually sit toward the lower end, provided client concentration is not too high.
Tax implications of maintaining and using a cash flow buffer
Holding a cash buffer does not itself create a tax liability. The cash sitting in a separate reserve or term deposit remains the business’s own money, and only interest earned on that balance is assessable income in the year it is received, taxed at the business’s normal rate.
The more important tax consideration is what the buffer is protecting you from. GST collected on sales, PAYG withheld from employee wages, and superannuation contributions are all amounts the business holds on behalf of others, the ATO or employees, rather than genuine business income. ATO guidance on managing business cash flow recommends setting these amounts aside in a dedicated account as they accrue, precisely because treating them as available operating cash is one of the most common ways small businesses end up with an unpayable tax debt.
Some businesses can also smooth cash flow through reporting frequency choices. ATO guidance on reporting cycles notes that switching to monthly GST reporting, where eligible, can reduce the size of individual payments by making them smaller and more frequent rather than quarterly and lumpy, which some businesses find easier to plan around.
Buffer strategies across different business sizes and sectors
A sole trader consultancy with low fixed costs and a short sales cycle typically needs the least complex approach: a 90-day fixed buffer covering rent, software and the owner’s minimum drawings, reviewed quarterly.
A small retail or hospitality business with seasonal trade and higher staff numbers tends to need the burn-rate and recovery-time method, because its worst month can be dramatically different from its average month, and a flat multiple risks leaving it short exactly when it needs cover most.
A trades or construction business, which often faces large, lumpy supplier payments and progress-payment delays from clients, benefits most from a strong obligations-first ring-fence alongside its operational buffer, since the gap between paying subcontractors and being paid by the client is often the single biggest cash risk in that sector.
A growing business with employees and a more complex super and PAYG obligation set should expect its buffer target to rise over time as fixed costs and statutory obligations grow, which is why the quarterly recalculation step matters more as a business scales rather than less. Guidance on sell or hold decisions for property illustrates a related principle: businesses and property investors alike tend to underestimate how quickly a thin cash position limits their options when a decision needs to be made quickly.
Model your buffer and recovery scenarios with WealthStacker
Working out the right buffer by hand across fixed costs, burn rate and recovery time is useful, but testing how different scenarios play out over months or years is harder to do with a spreadsheet alone. We built a tool to let you run that modelling automatically rather than rebuilding formulas every time your numbers change.
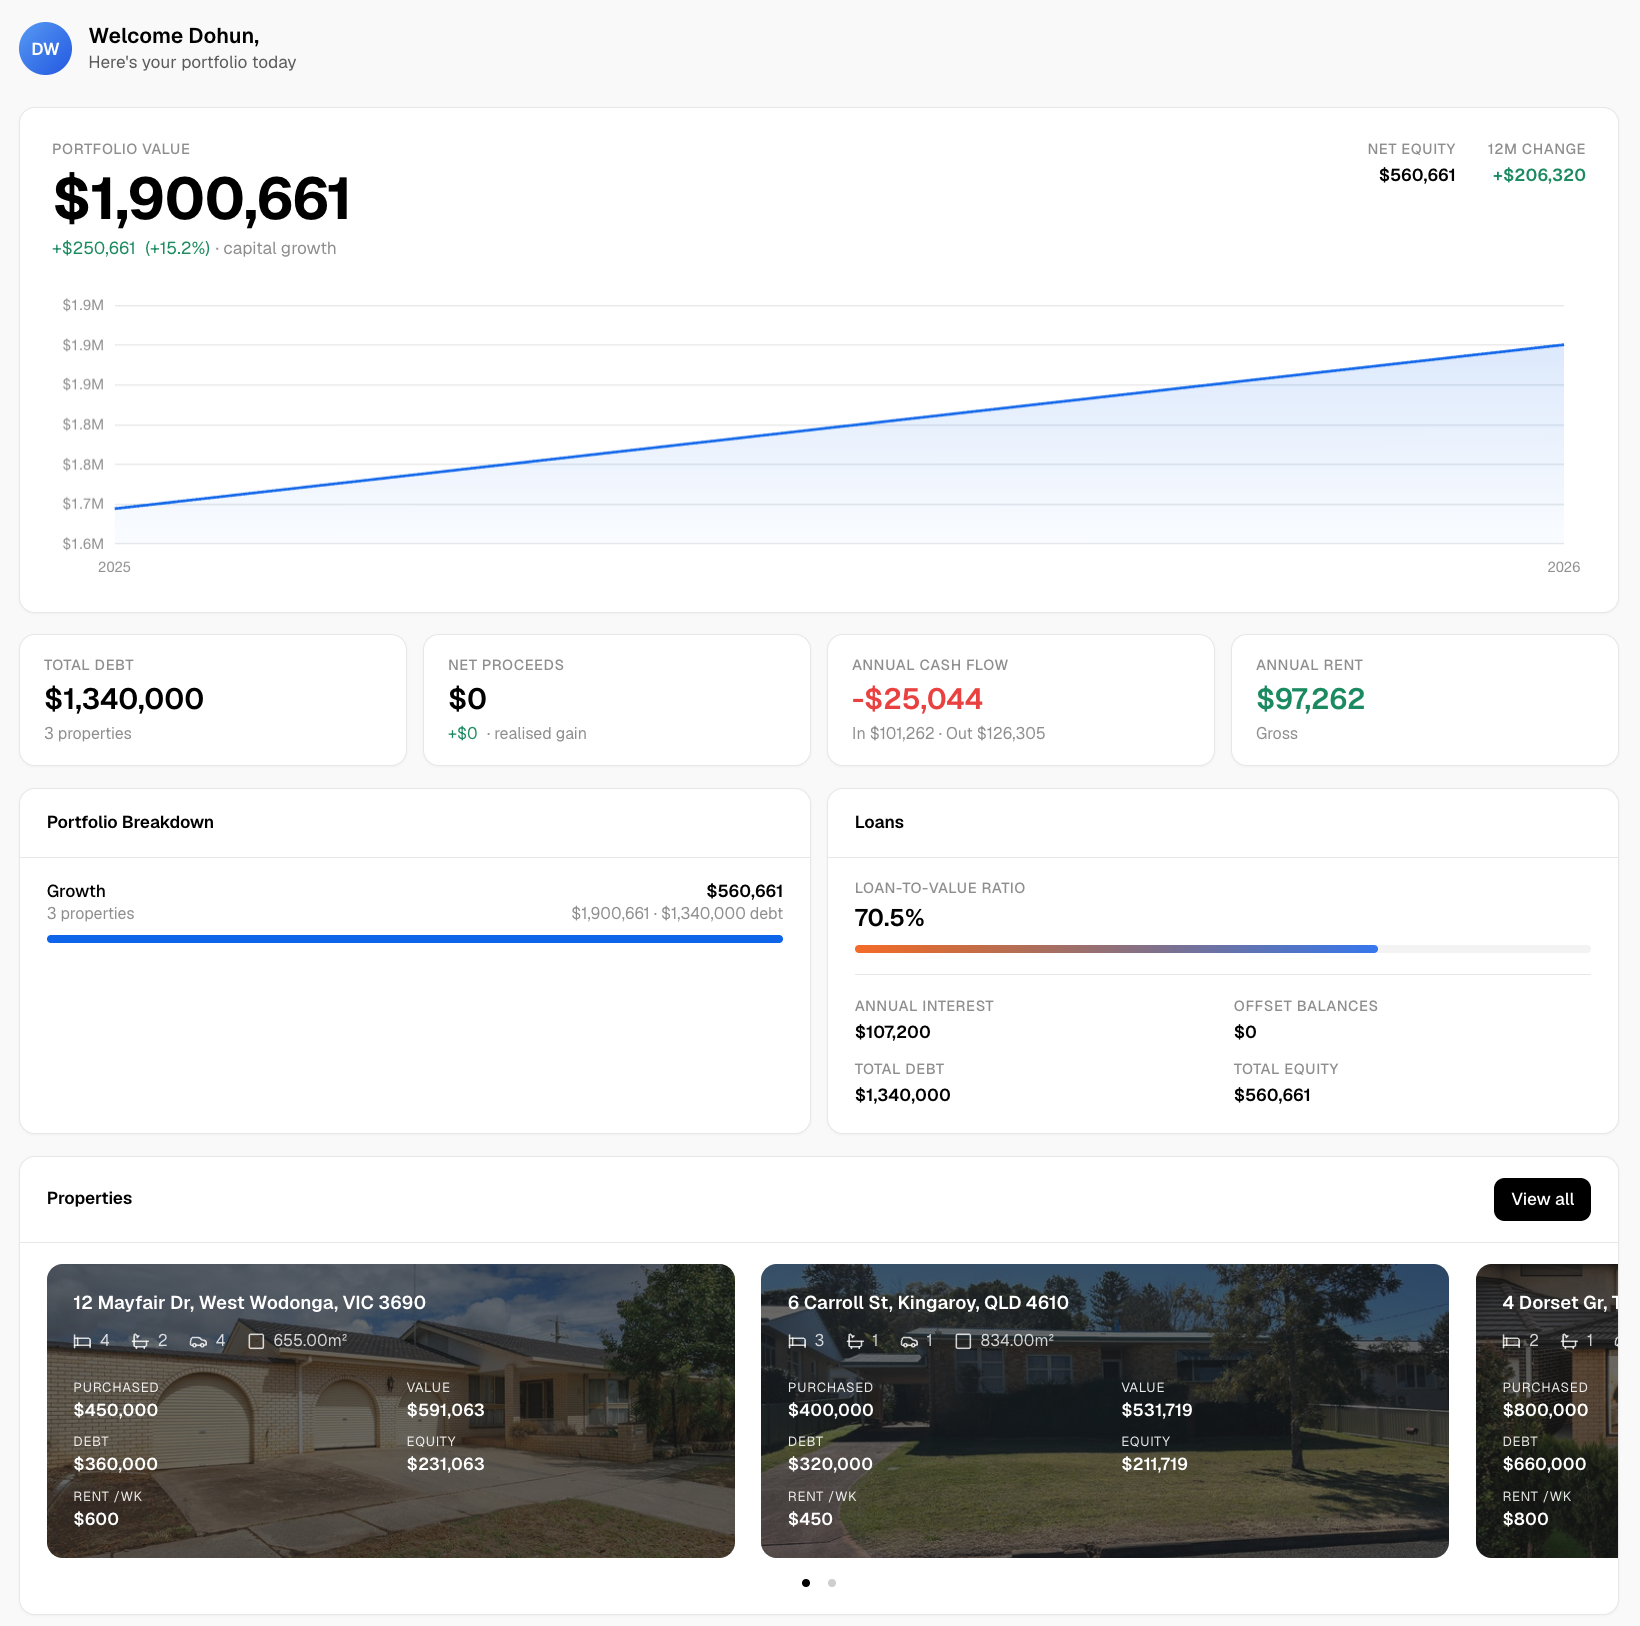
With WealthStacker, we provide free automated quarterly valuations and AI-assisted scenario modelling that was originally designed for property and investment decisions, and the same underlying “what-if” approach applies directly to cash flow planning:
- Run burn-rate and recovery-time scenarios to see how different buffer sizes hold up under a slow quarter.
- Compare how a larger reserve affects your broader financial position and borrowing capacity over time.
- Adjust inputs as your costs or obligations change, without rebuilding a forecast from scratch each quarter.
If you want a faster way to see how your buffer decisions play out before committing real cash to them, explore WealthStacker and start testing your own numbers.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
How much cash buffer should I have?
A reasonable starting point is one to three months of operating costs for a stable business, rising to three to twelve months for a seasonal or higher-risk business. The more reliable approach is to calculate it from your net monthly burn rate multiplied by a realistic recovery time, then add a margin for forecast error.
What is the 70/20/10 rule for money?
The 70/20/10 rule is a general personal budgeting guide that allocates 70% of income to living expenses, 20% to savings, and 10% to debt repayment or giving. It is not a business cash flow framework, and small business owners are better served by the fixed-months or burn-rate methods described above, which account for actual operating costs and statutory obligations rather than a fixed percentage split.
What is a good cash flow amount for a small business?
There is no single “good” amount, since it depends on your fixed costs, revenue volatility and statutory obligations like GST, PAYG and super. A good starting benchmark is enough to cover 90 days of operating costs plus a fully funded, separately held allowance for upcoming tax and super payments, as recommended in ATO cash flow guidance.
What is a cash buffer?
A cash buffer is money held separately from everyday operating funds specifically to cover costs if revenue drops or an unexpected bill arrives. It differs from working capital and from a credit facility, because it is cash you already hold rather than money you borrow, which ASIC’s guidance for directors ties directly to a business’s ability to pay debts as they fall due.
How often should I review my buffer target?
Review your buffer target at least quarterly, with a weekly reconciliation of actual cash against your forecast in between. Business.gov.au’s cash flow tools recommend this cadence so the target stays aligned with current costs rather than a figure calculated months earlier.
Sources
- Helping small business directors respond early to financial difficulty | ASIC
- Manage your business cash flow | ATO
- Business